

- by Ahmed Shareek
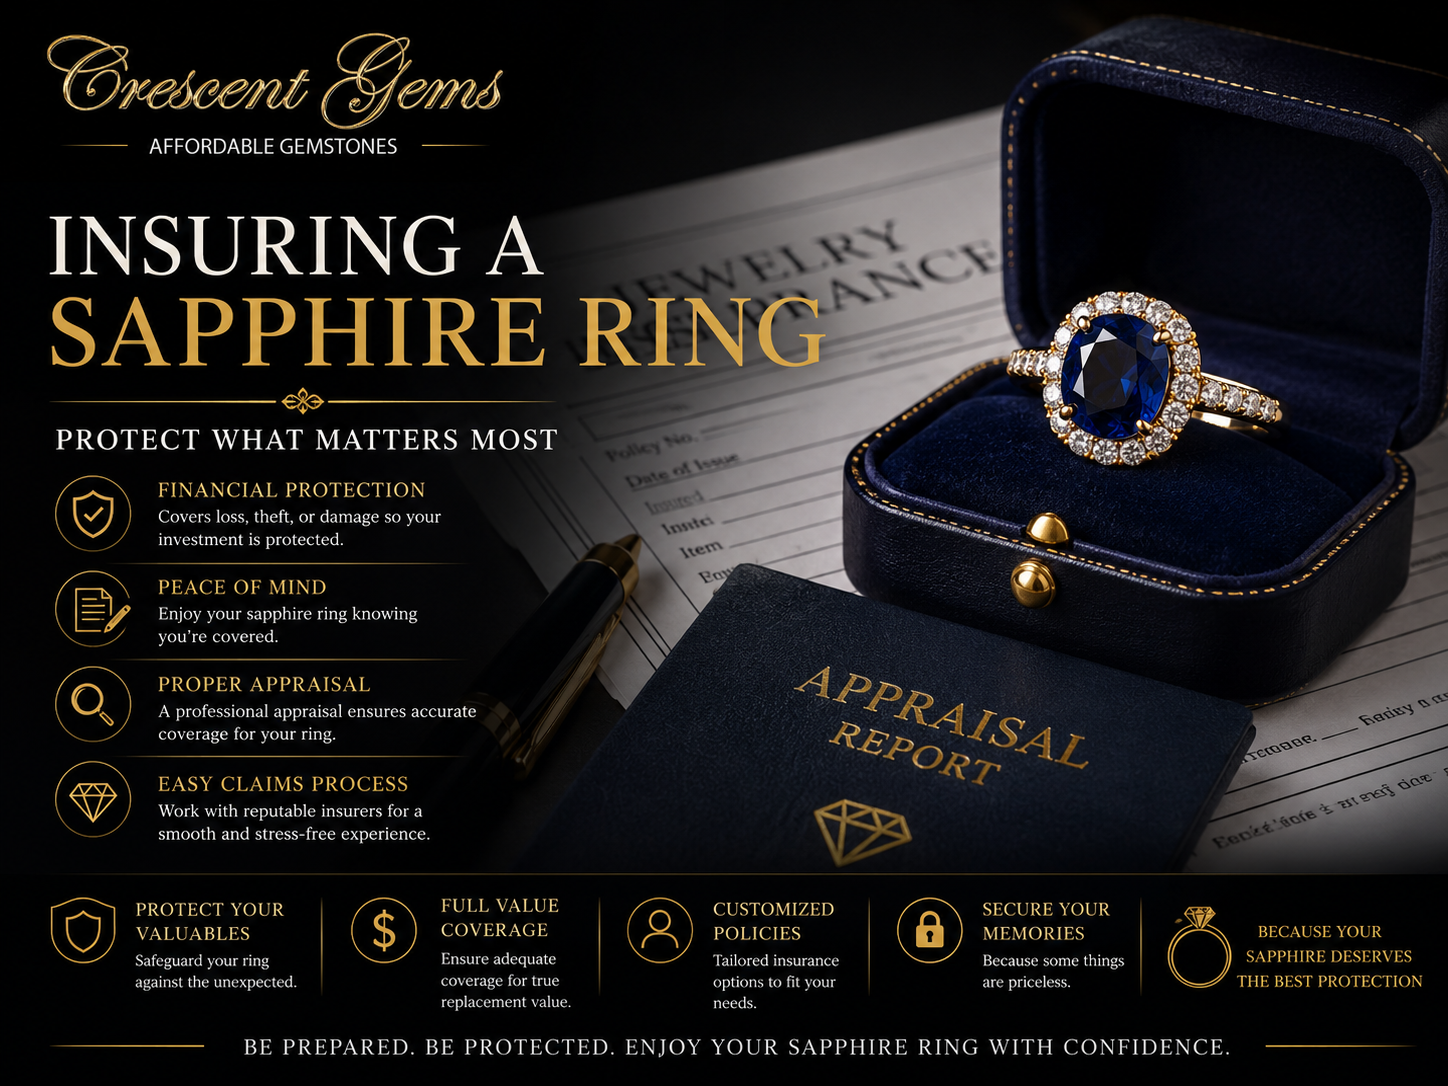
Insuring a Sapphire Ring — Appraisals, Riders, and What Your Policy Actually Covers
- by Ahmed Shareek
For ring care alongside insurance: How to Care for a Sapphire Ring. For stone documentation: How to Read a GIA Sapphire Report. For the buying foundation: Ultimate Sapphire Buying Guide.

Most buyers spend considerable time and care choosing a sapphire engagement ring and almost no time thinking about what happens if it is lost, stolen, or damaged. Insurance is not a glamorous subject, but for a ring that represents a significant purchase — typically $1,000 to $15,000 and sometimes much more — it is one of the most financially important decisions you make after the purchase.
A proper insurance appraisal should include: a detailed description of the center stone (species, carat weight, measurements, color, clarity, treatment status from the laboratory report); a detailed description of the setting (metal type and karat, setting style, accent stones); reference to any existing laboratory report by report number; photographs; the appraiser's stated retail replacement value; and the appraiser's credentials, signature, and date.
Who should appraise it: Use a credentialed, independent appraiser — not the jeweler who sold you the ring. In the United States that means a GIA Graduate Gemologist (GG) who also holds an appraisal credential: the National Association of Jewelry Appraisers (NAJA), the American Society of Appraisers (ASA) Master Gemologist Appraiser, or the American Gem Society (AGS) Certified Gemologist Appraiser. Elsewhere the equivalent bodies differ — the Institute of Registered Valuers in the UK, the National Council of Jewellery Valuers in Australia and New Zealand, the Canadian Gemmological Association in Canada, and the Association of Independent Jewellery Valuers internationally. US independent appraisers typically charge $50-$150 per hour or $50-$200 per item; fees elsewhere vary.
Retail replacement value: Insurance appraisals typically state a retail replacement value — often higher than what you paid if you bought from a direct-source dealer like Crescent Gems. Do not ask the appraiser to lower the value to match what you paid. Update your appraisal every two to three years or sooner if sapphire prices have moved significantly.
The two options below describe the United States and Canada, where this pattern — an independent appraisal, then either a scheduled rider or a standalone jewelry policy — is the norm. Practice elsewhere is different, and the section after them says how.
Homeowner's or Renter's Insurance — Scheduled Item Rider (United States): US homeowner's and renter's policies typically cap theft of jewelry at around $1,000-$2,500 in total, however large the contents limit. A scheduled jewelry rider lists each item individually with its appraised value. Costs typically 1-2% of appraised value annually. May carry a deductible. Verify whether mysterious disappearance is covered and whether it's replacement value or actual cash value.
Standalone Jewelry Insurance: Dedicated jewelry insurance companies (Jewelers Mutual, GemShield, Lavalier) specialize exclusively in fine jewelry. Key features: agreed value coverage; worldwide coverage; mysterious disappearance coverage; no deductible options. Annual premium typically 1-2% of appraised value.
The framework above is a US one and does not transfer. In Germany, jewelry sits inside the Hausratversicherung as Wertsachen, normally limited to a percentage of the sum insured (commonly around 20%), with higher limits conditional on storage in an approved safe rather than on an appraisal. In Japan, household contents cover treats a single item above ¥300,000 as a 明記物件 (declared item) that must be listed by name, with a default aggregate limit per event and optional higher tiers. France, the Gulf states and the UK each run their own conventions on declaration thresholds, safe requirements and who may value a stone. Before relying on any figure on this page, confirm the rule with your own insurer in your own country — the documentation advice below travels, the policy mechanics do not.
The terms below are those of a US dedicated jewelry policy; a homeowner's rider is usually narrower, and cover outside the US varies. Theft: covered. Loss (mysterious disappearance): covered by dedicated jewelry insurers — this is the most important coverage term for rings, since most ring loss is unexplained. Accidental damage: covered. Normal wear and gradual deterioration: not covered. Intentional damage: not covered. The phrase “mysterious disappearance” on your policy is critical — verify it is explicitly included.
Replacement value (agreed value): The policy pays the full appraised value to replace the item with an equivalent piece, regardless of depreciation. This is what you want for fine jewelry. Actual cash value (ACV): The policy pays what the item is worth at the time of the claim, adjusted for depreciation. For fine sapphire jewelry, ACV is the weaker basis: it settles at a depreciated figure, which will not fund an equivalent replacement at current retail. Verify which basis your policy specifies before you need it.
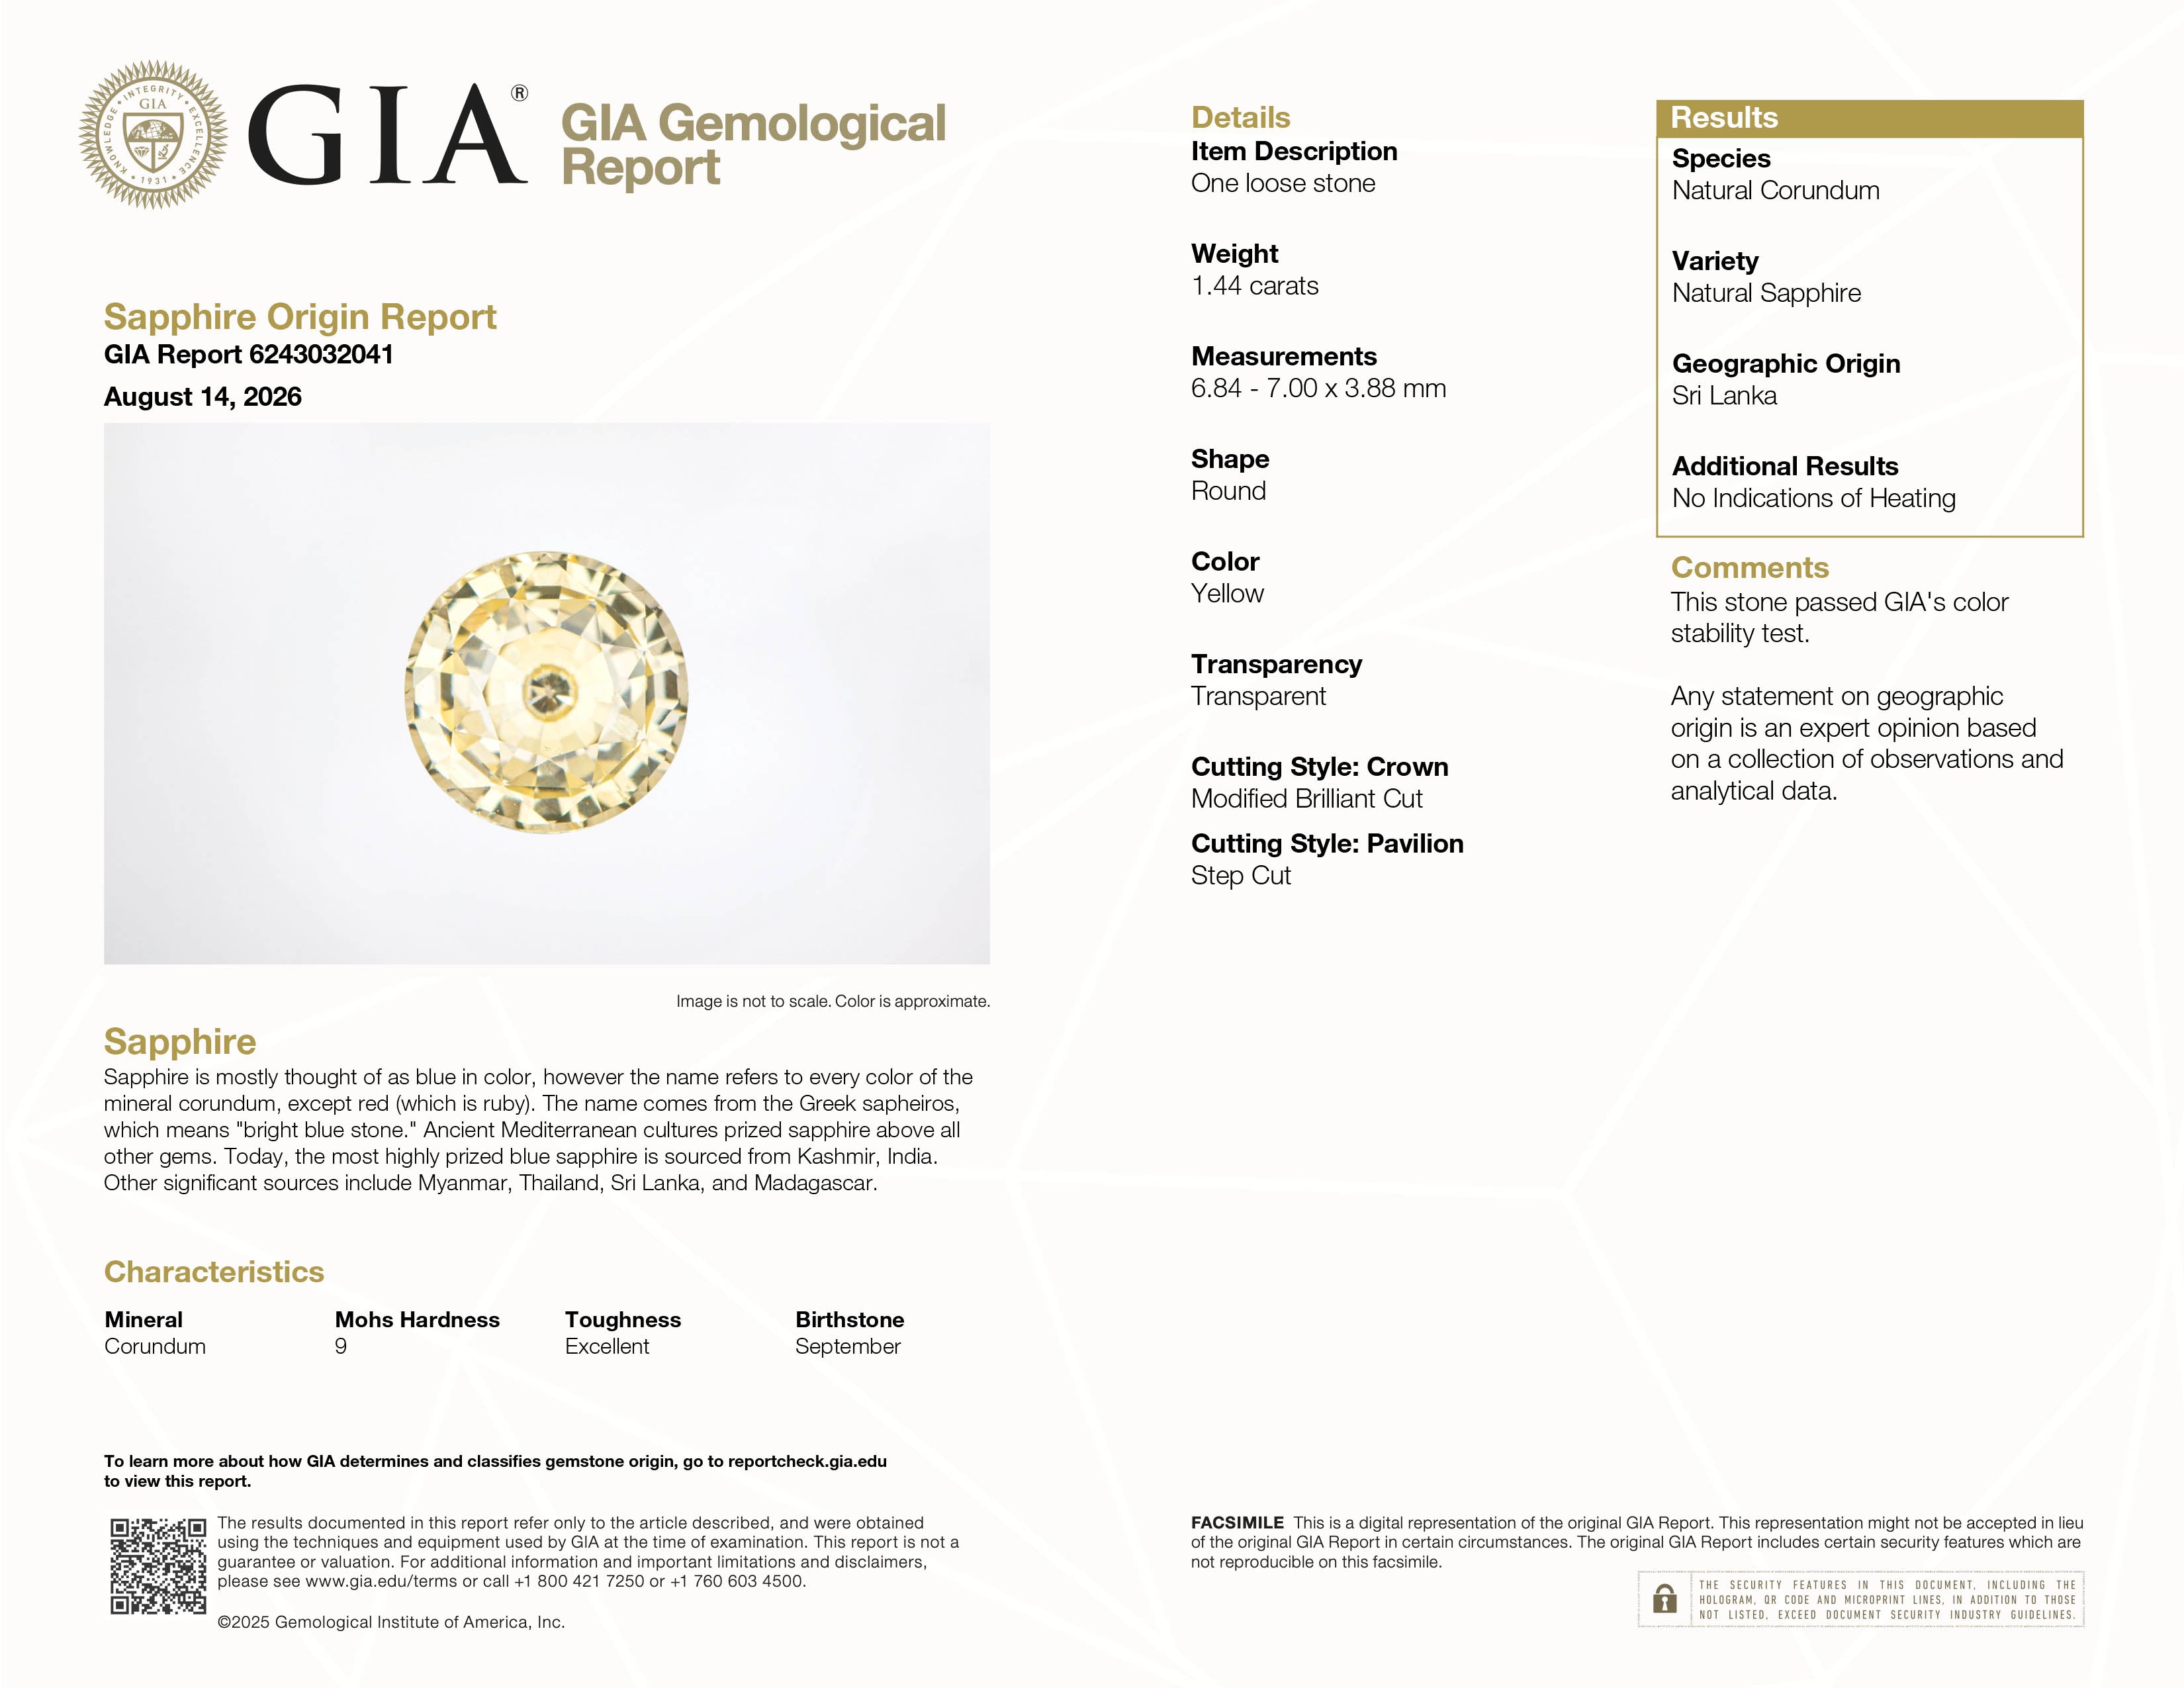
Keep: the GIA or laboratory report for the center stone (see our GIA report guide); the insurance appraisal; the purchase receipt or invoice; photographs from multiple angles; video. Store all documentation somewhere other than your home — a password-protected cloud folder works well. If the ring contains an unheated sapphire, explicitly draw your appraiser's attention to the GIA report's unheated designation so they factor in the unheated premium, not generic heated market rates.
Have your ring inspected professionally annually to check prong tightness, setting integrity, and any signs of wear. Prompt repair of damage prevents further loss. Keep appraisals updated. See our Sapphire Ring Care Guide for the full maintenance framework.
Report theft to police immediately. Contact your insurer promptly. Gather your documentation. Understand your replacement options — most dedicated jewelry insurance policies offer cash payment at the appraised value, or in-kind replacement through a jeweler of your choice. For damaged rings, get a repair estimate from a qualified jeweler before accepting any settlement.
Expect to pay 1-2% of the appraised value per year for a dedicated jewelry insurance policy with replacement value coverage and no deductible. For a ring appraised at $5,000: $50-$100/year. For a ring appraised at $15,000: $150-$300/year. For context on ring and stone values, see our what a good 1 carat costs and what a good 2 carat costs guides.
Questions about your specific stone's value or documentation? Email crescentgems@gmail.com — we respond within one business day.

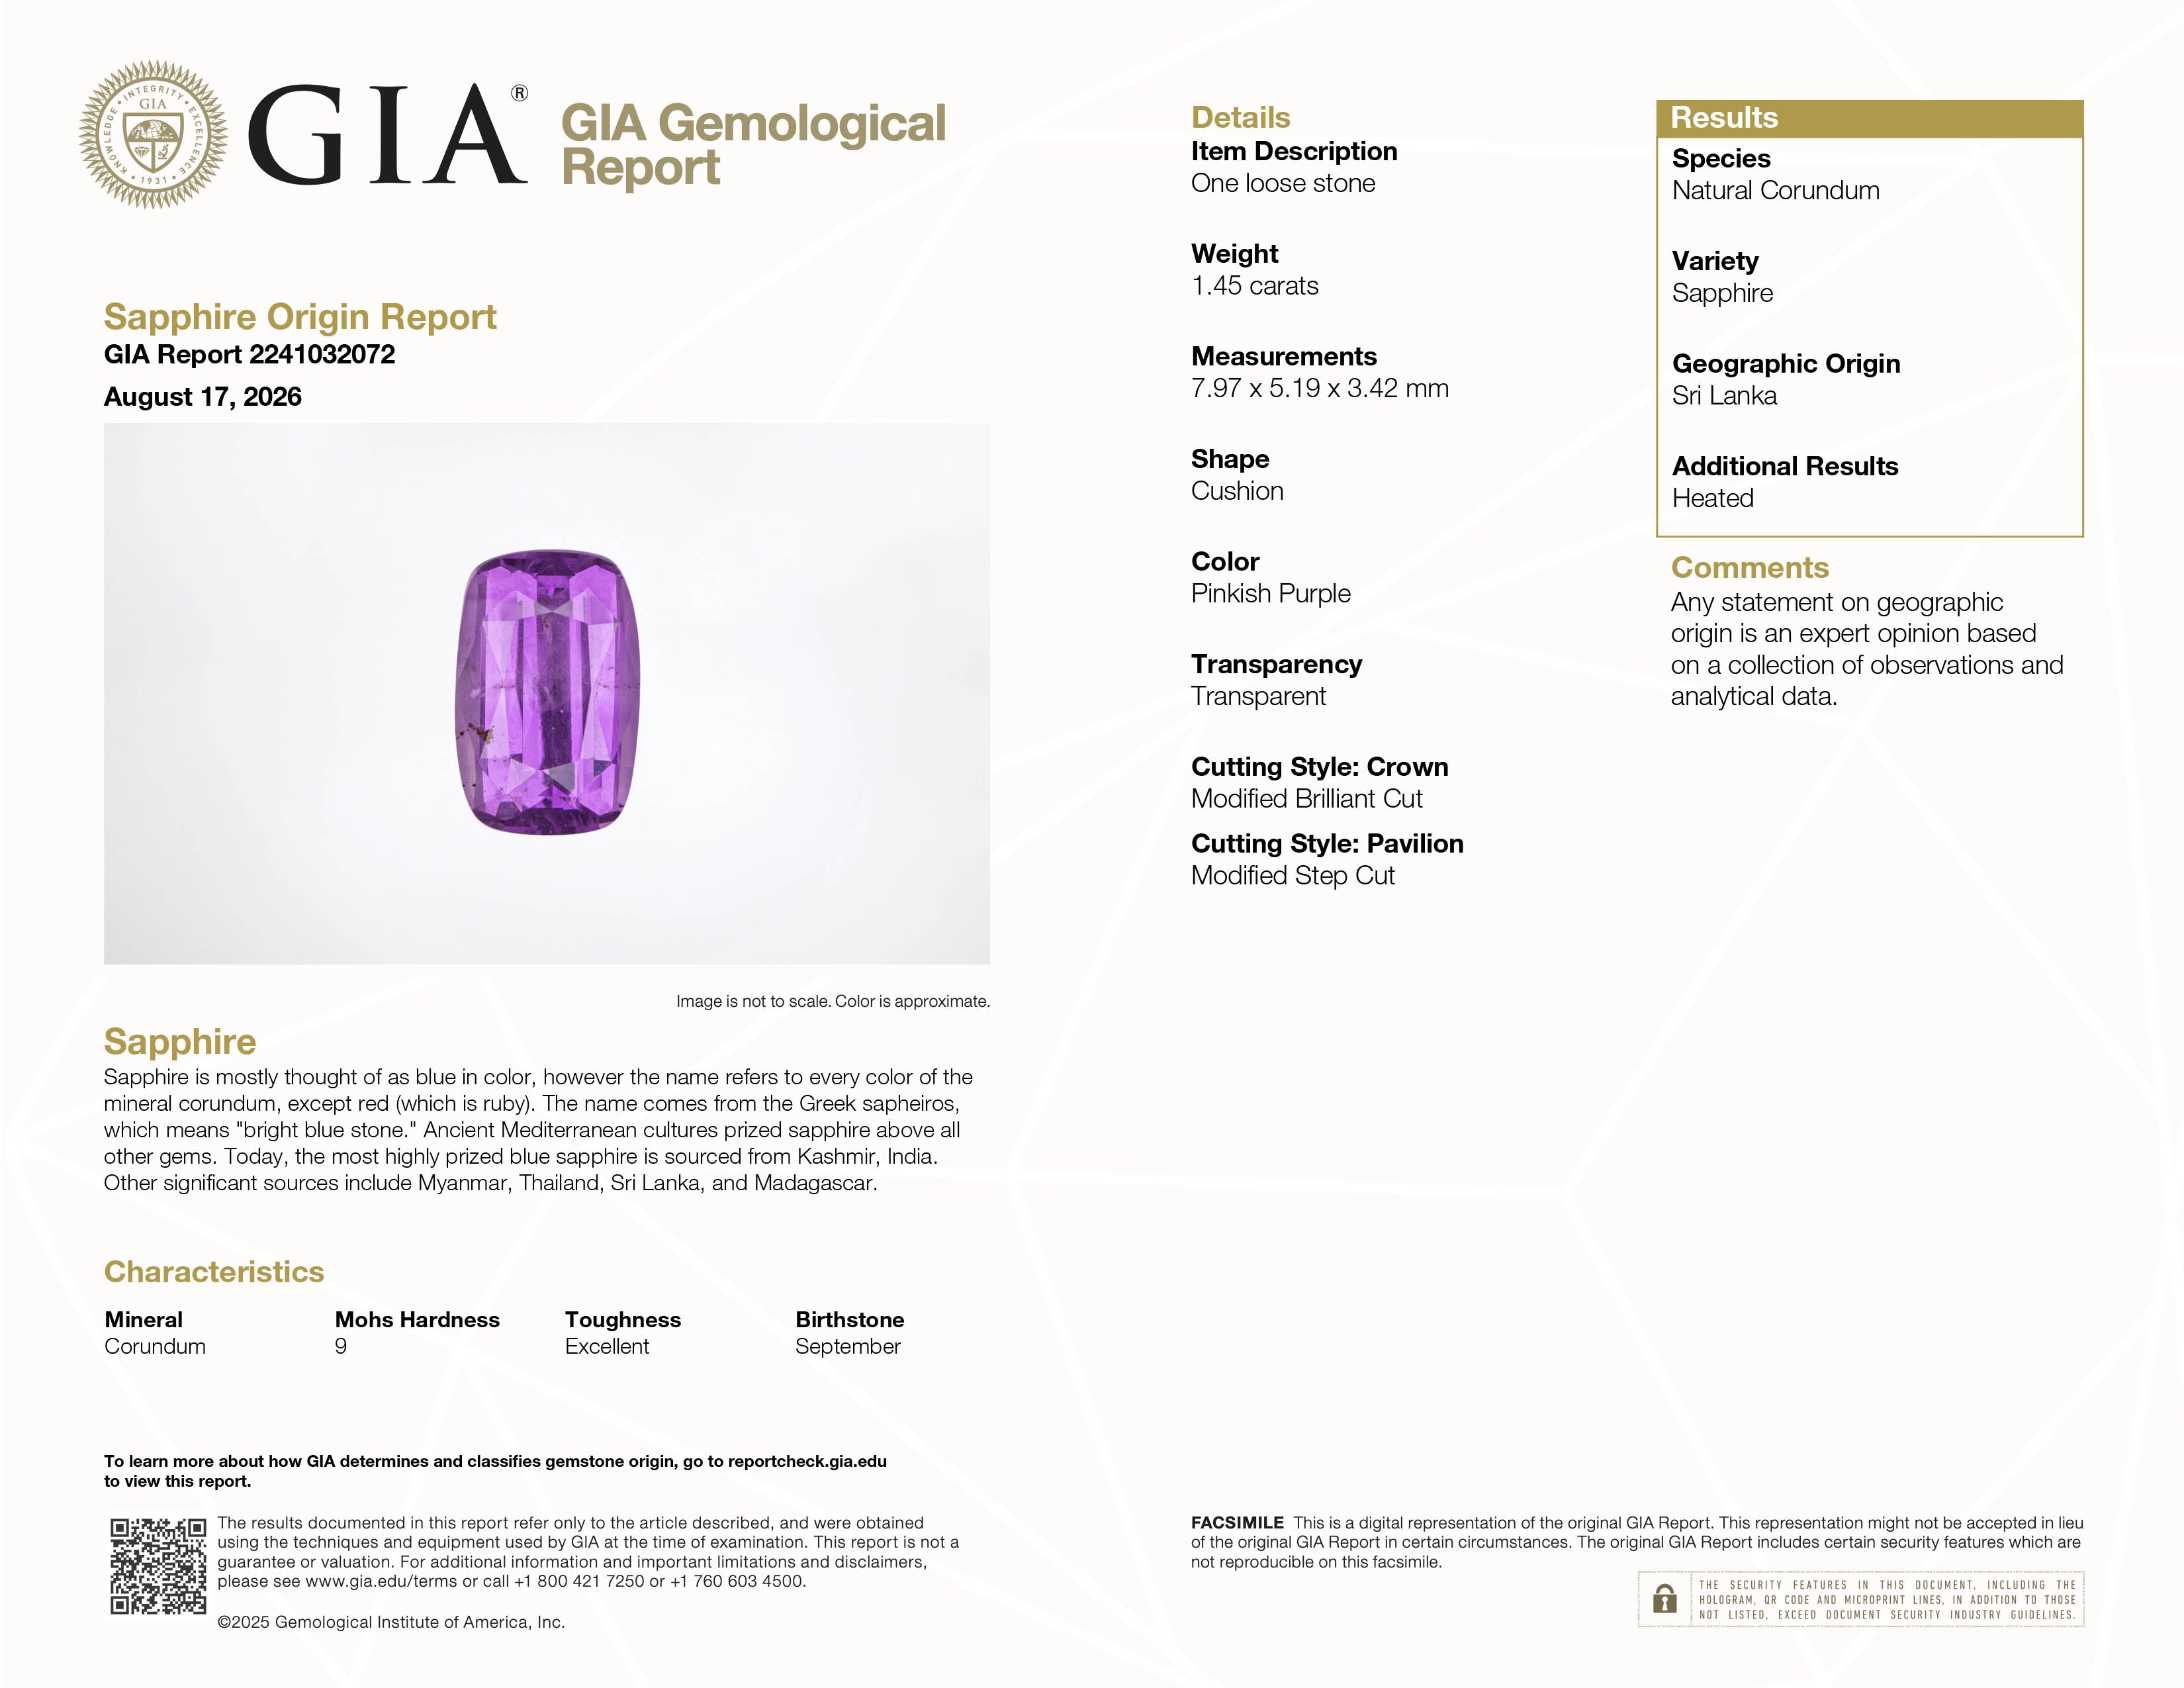
CG8469
ピンキッシュパープルサファイア 1.45ct 【加熱】 スリランカ産 GIA原産地レポート付
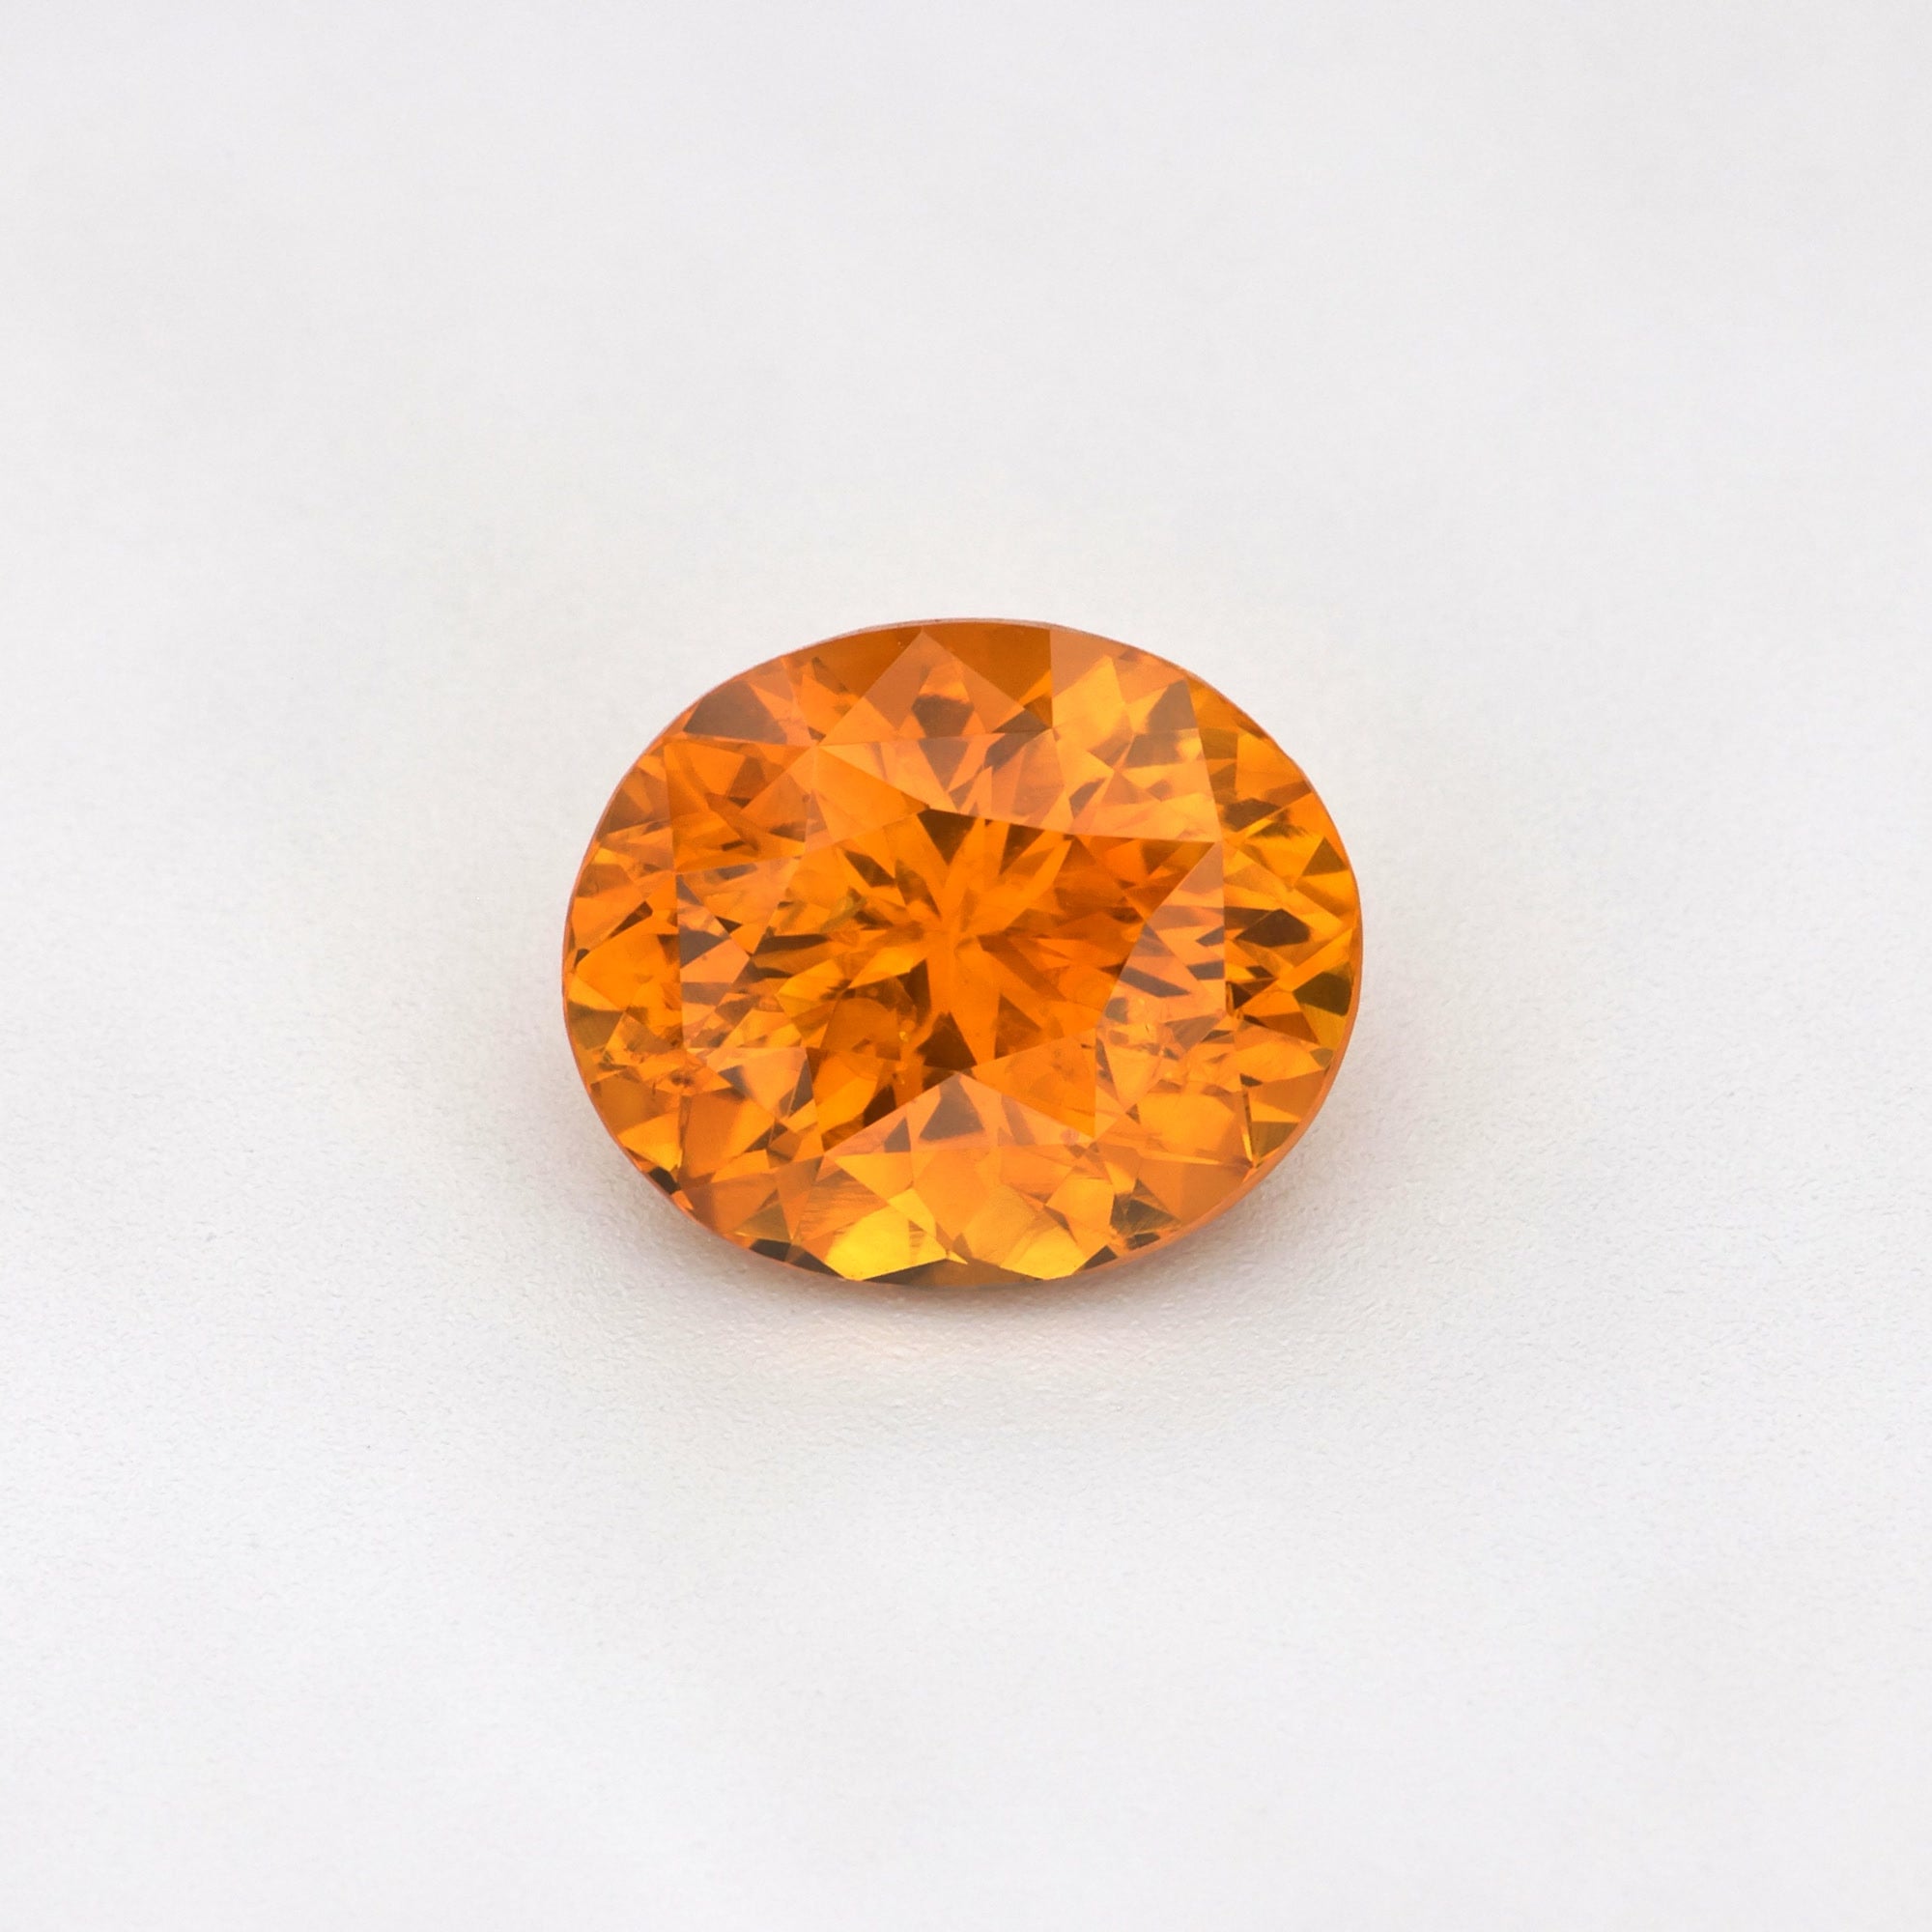
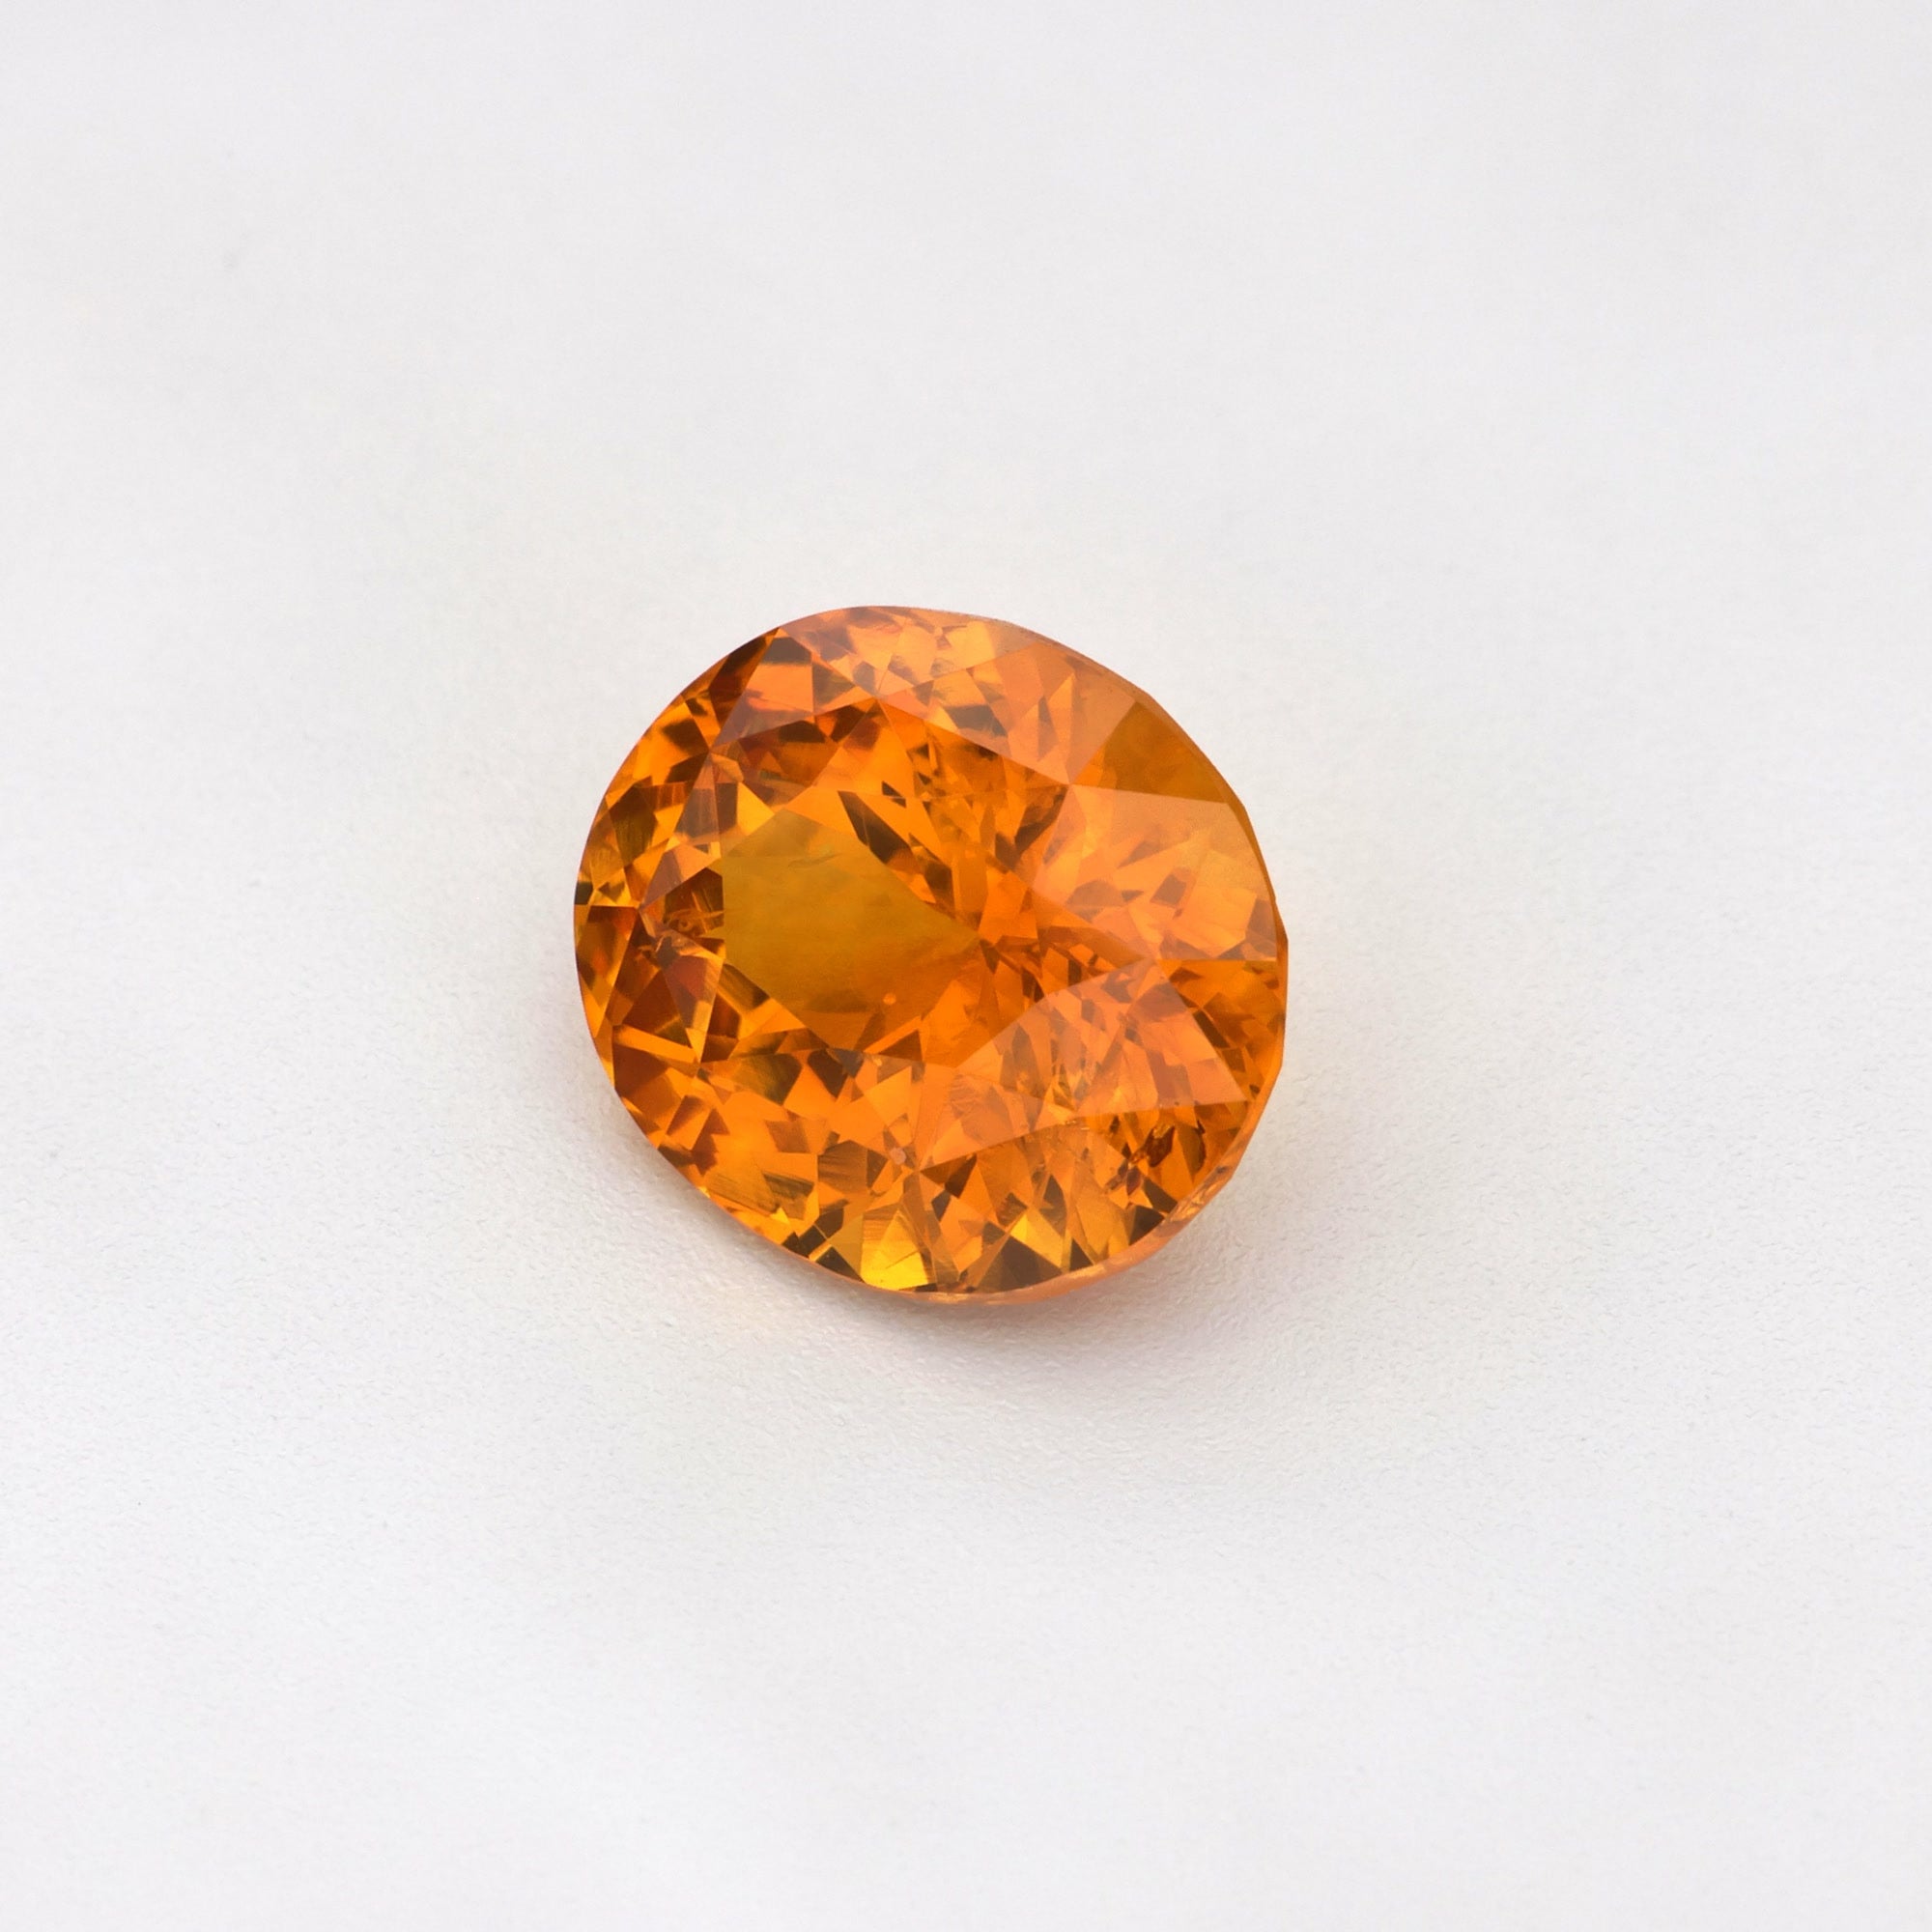
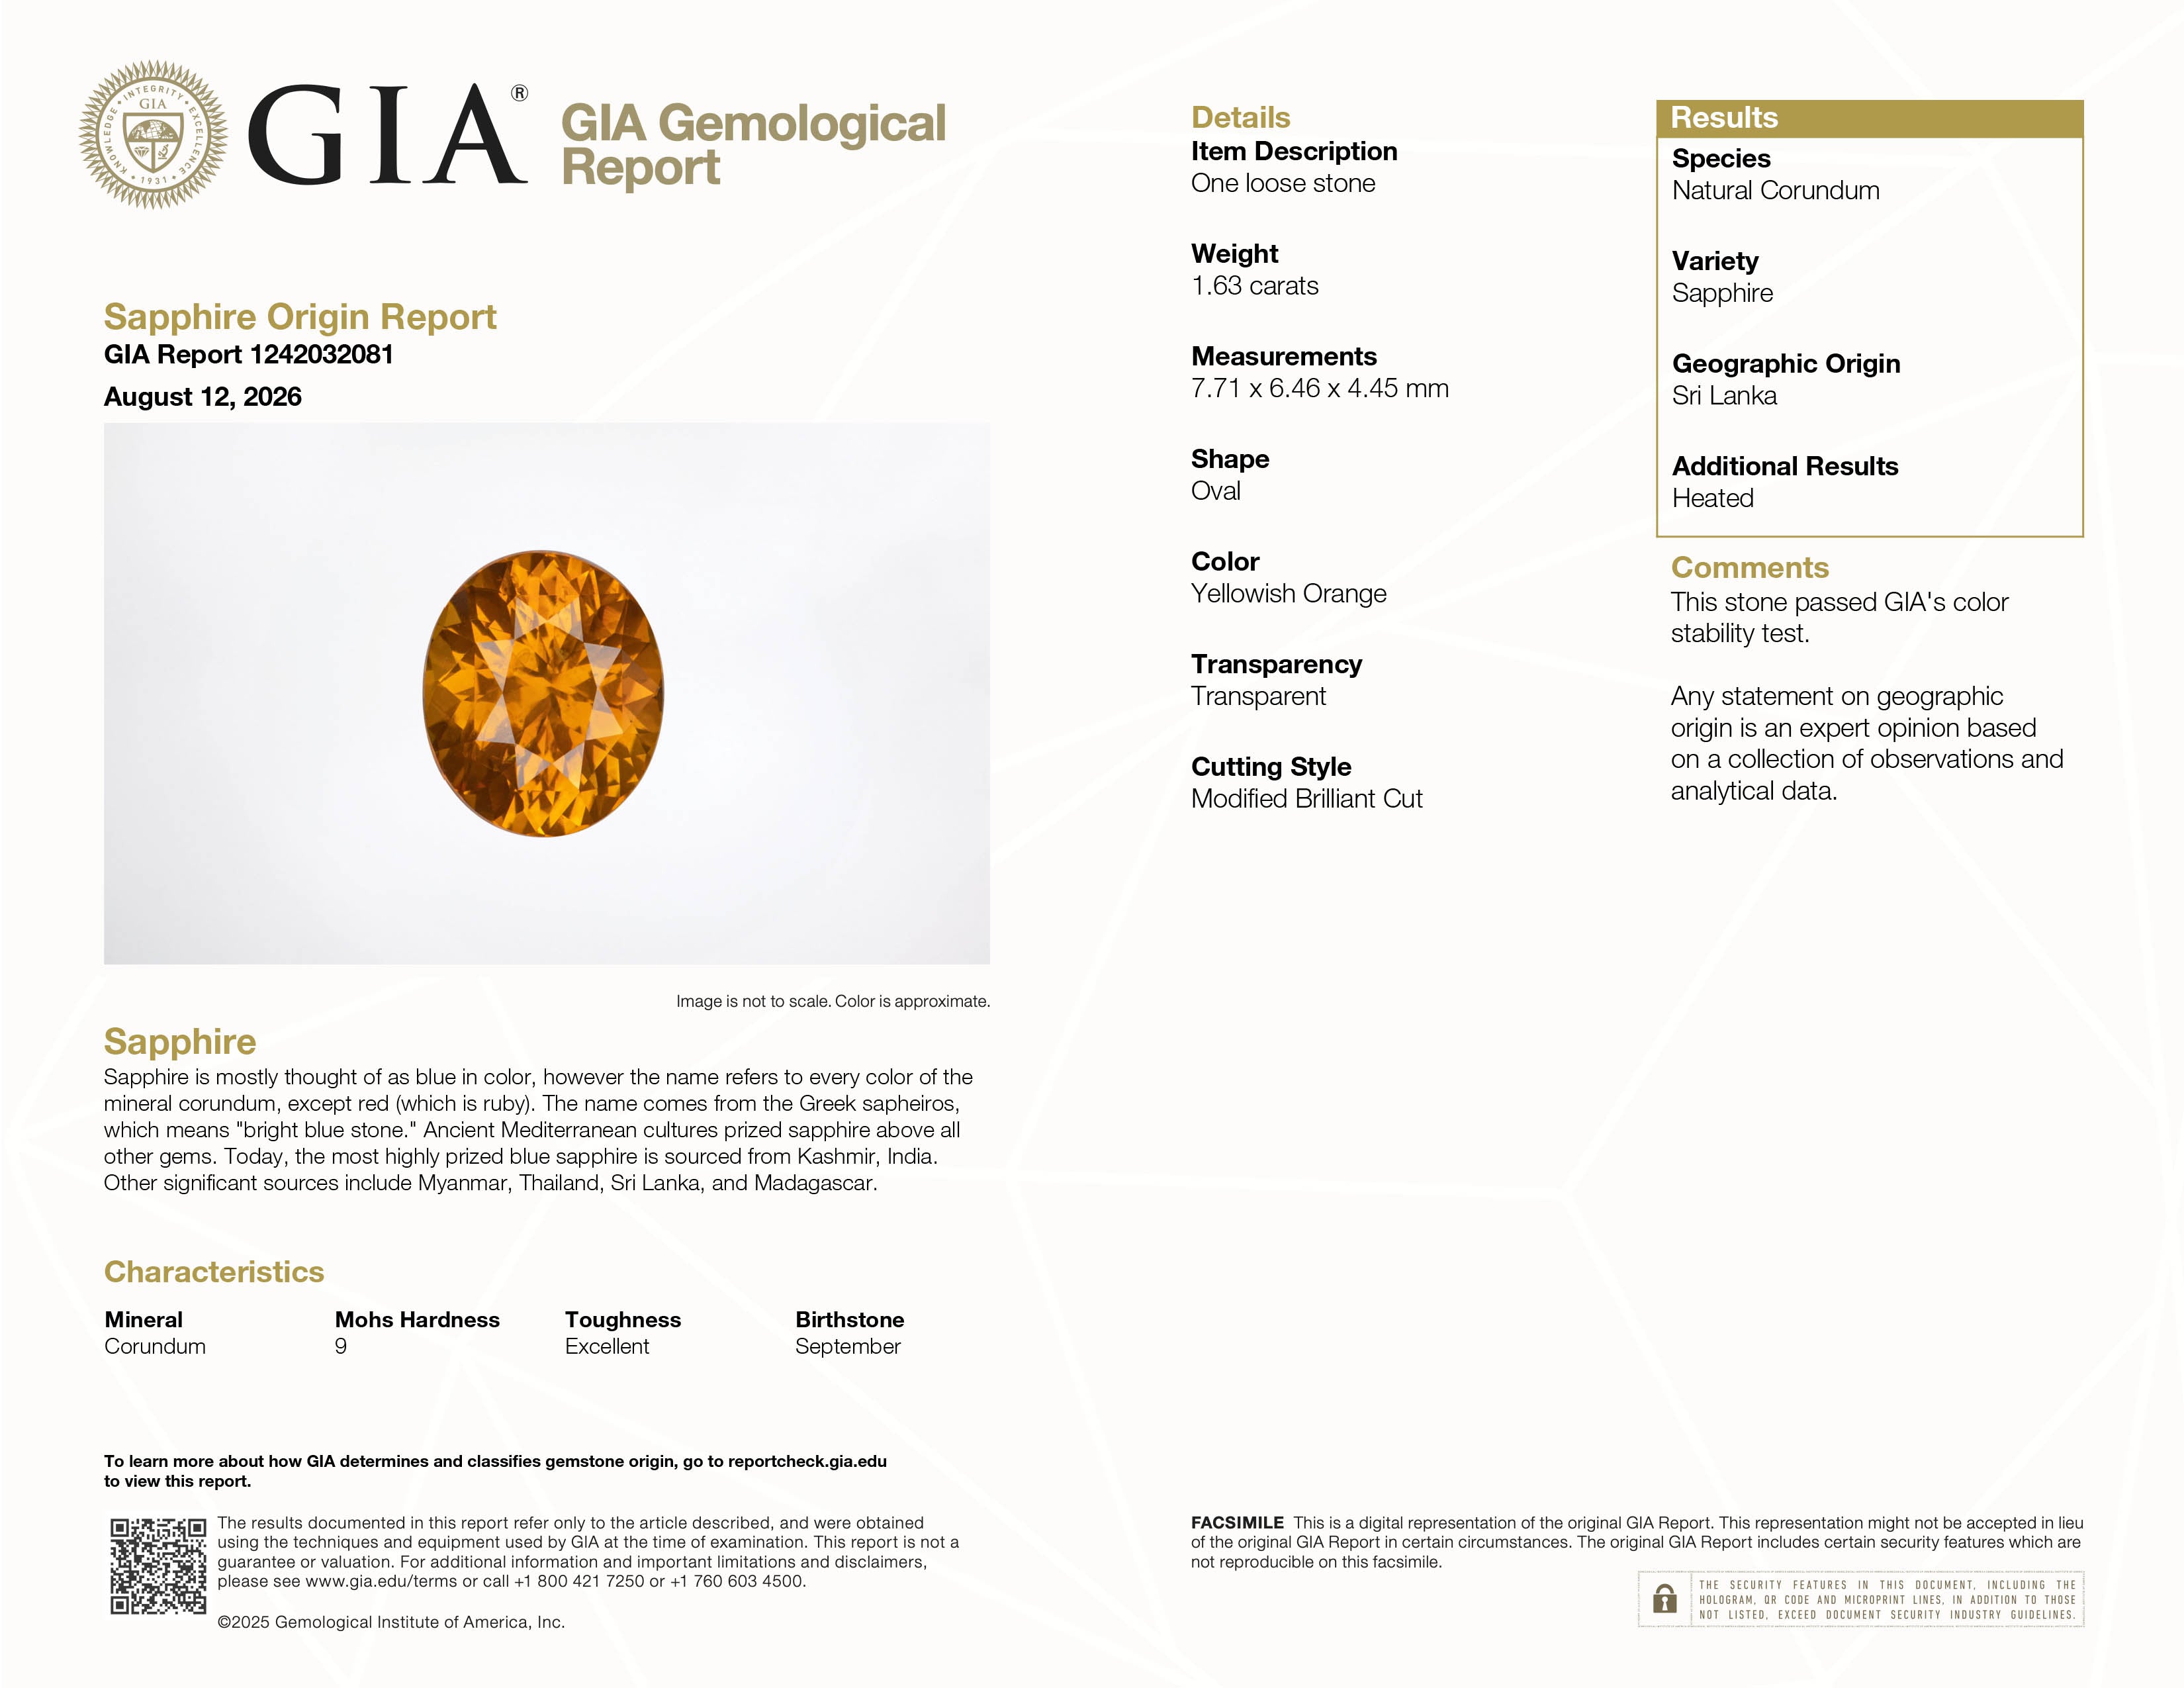
CG8454
天然オレンジサファイア1.63ct・オーバルカット・GIAレポート付・産地スリランカ(レポート記載)
CG8468
CG8465
CG8464
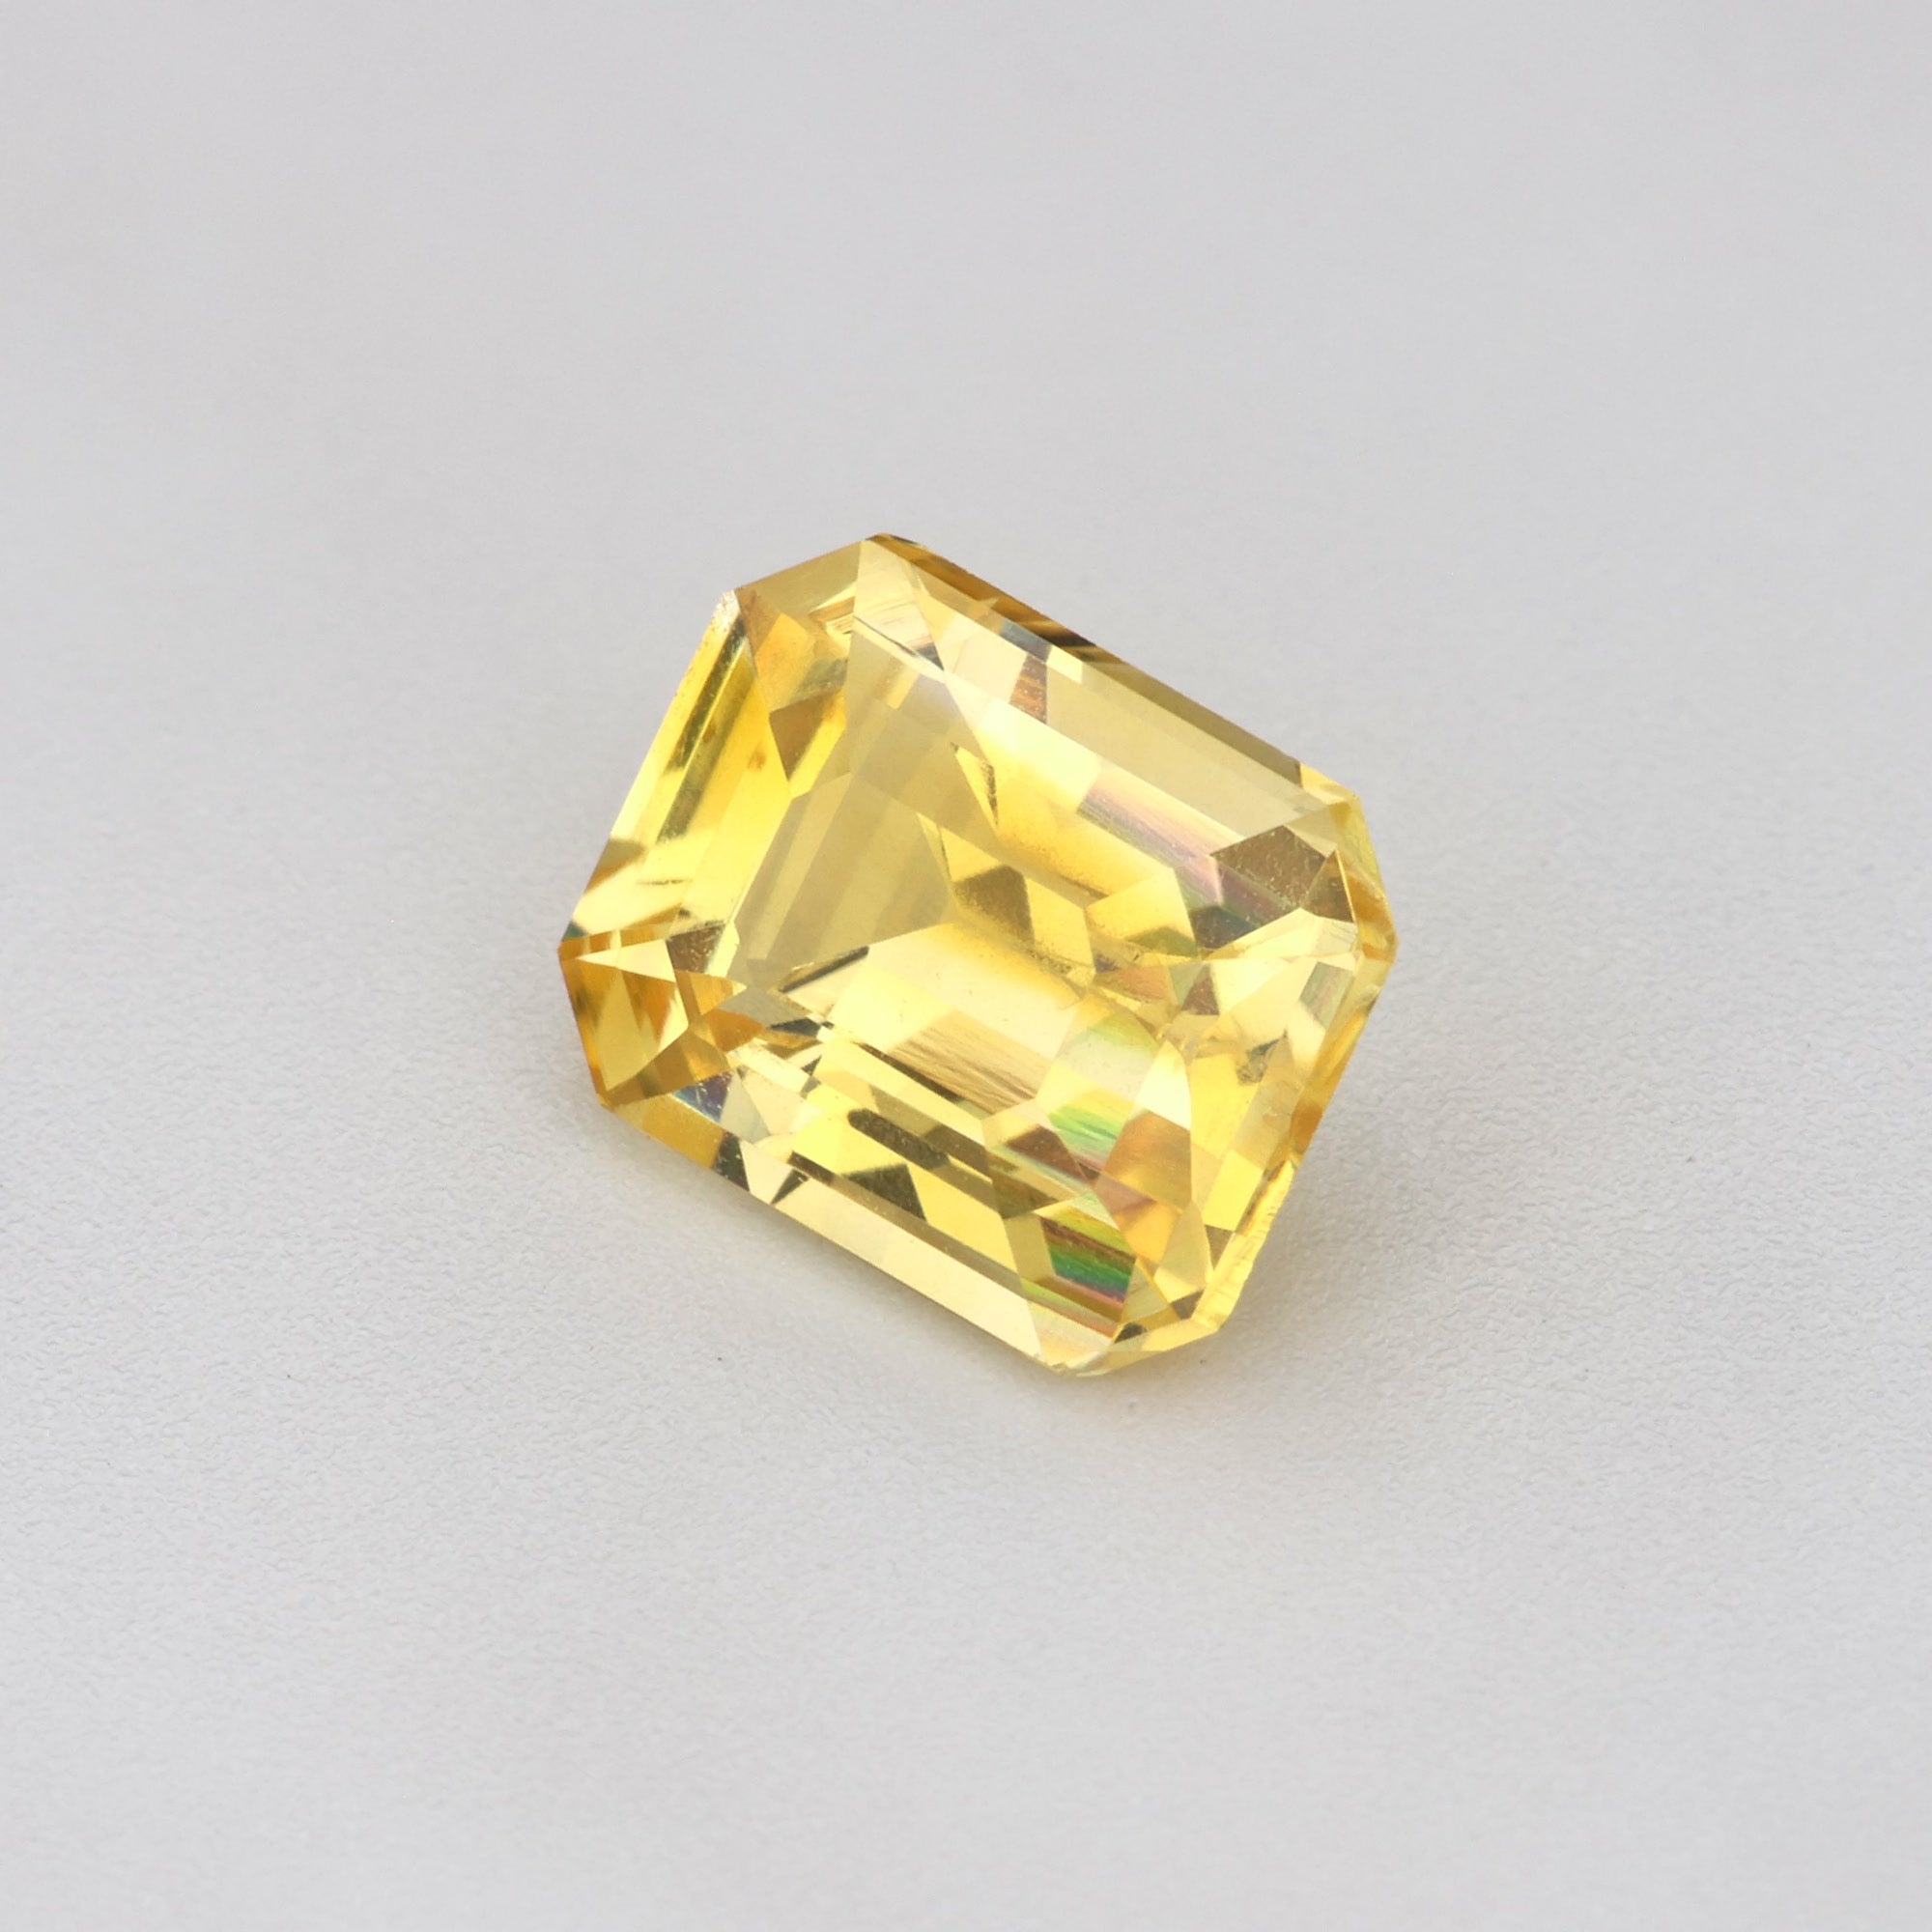
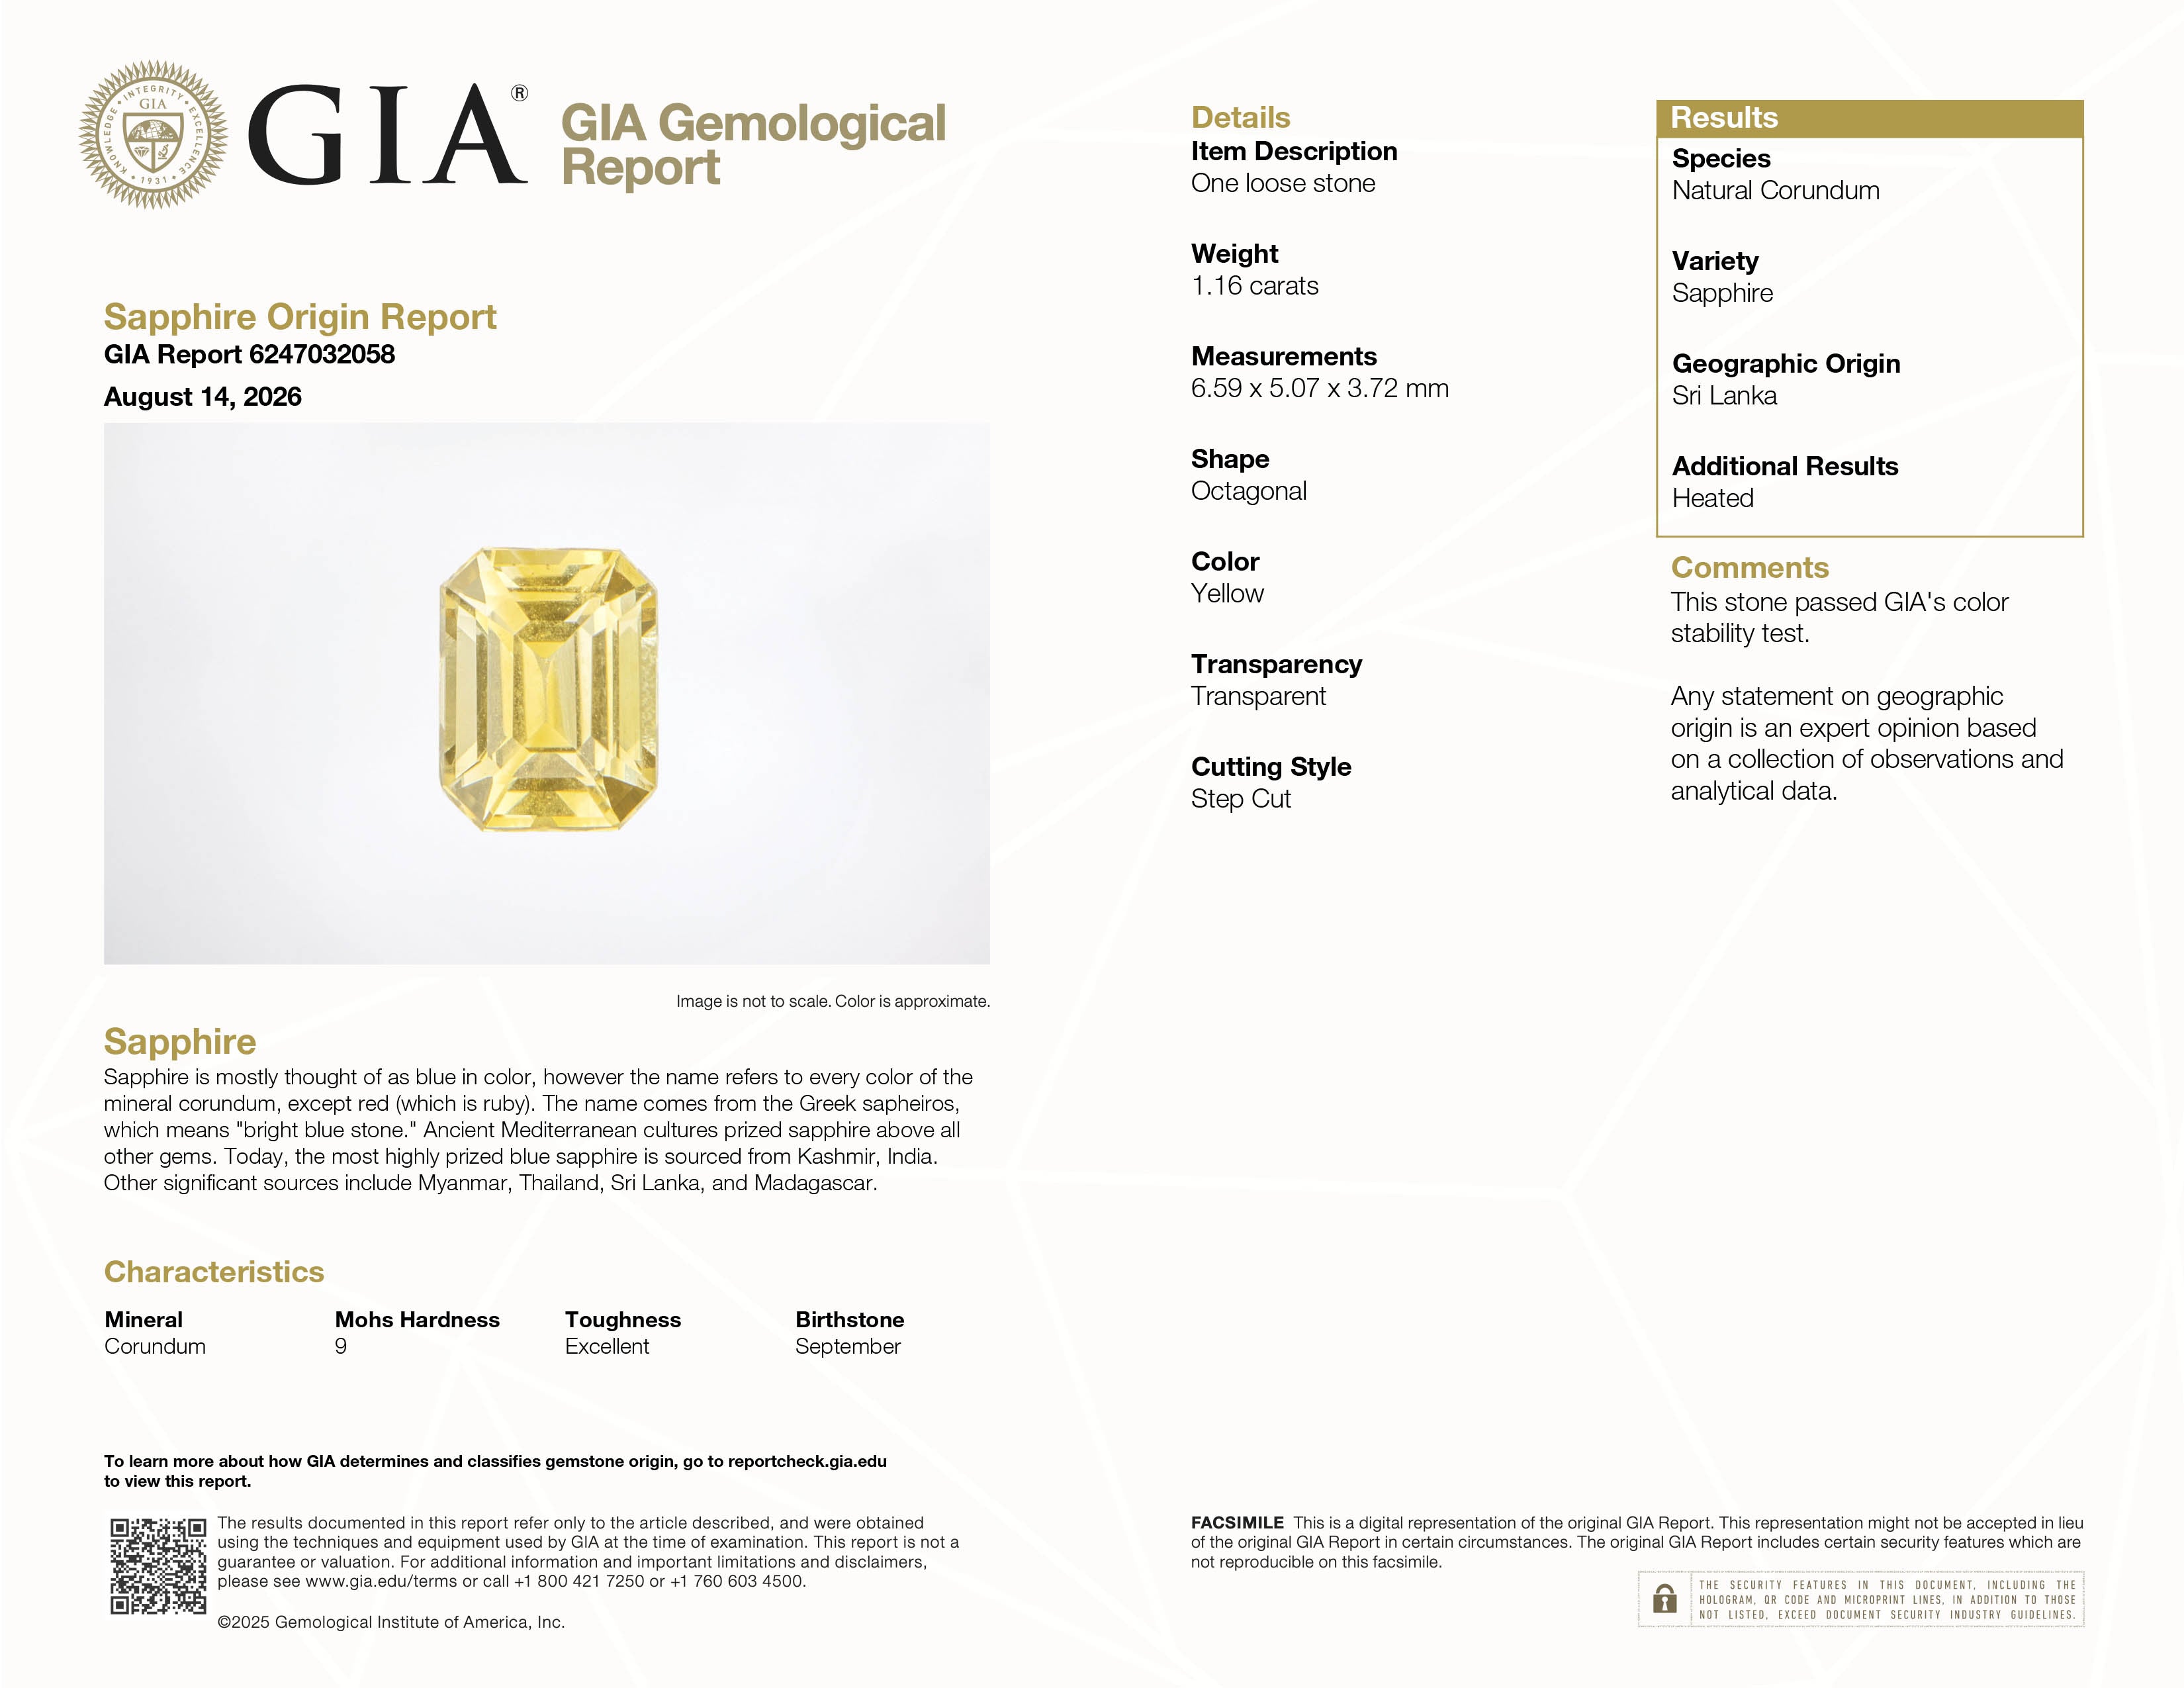
天然イエローサファイア 1.16ct スリランカ産 エメラルドカット【GIA原産地レポート付】ルース
CG8463
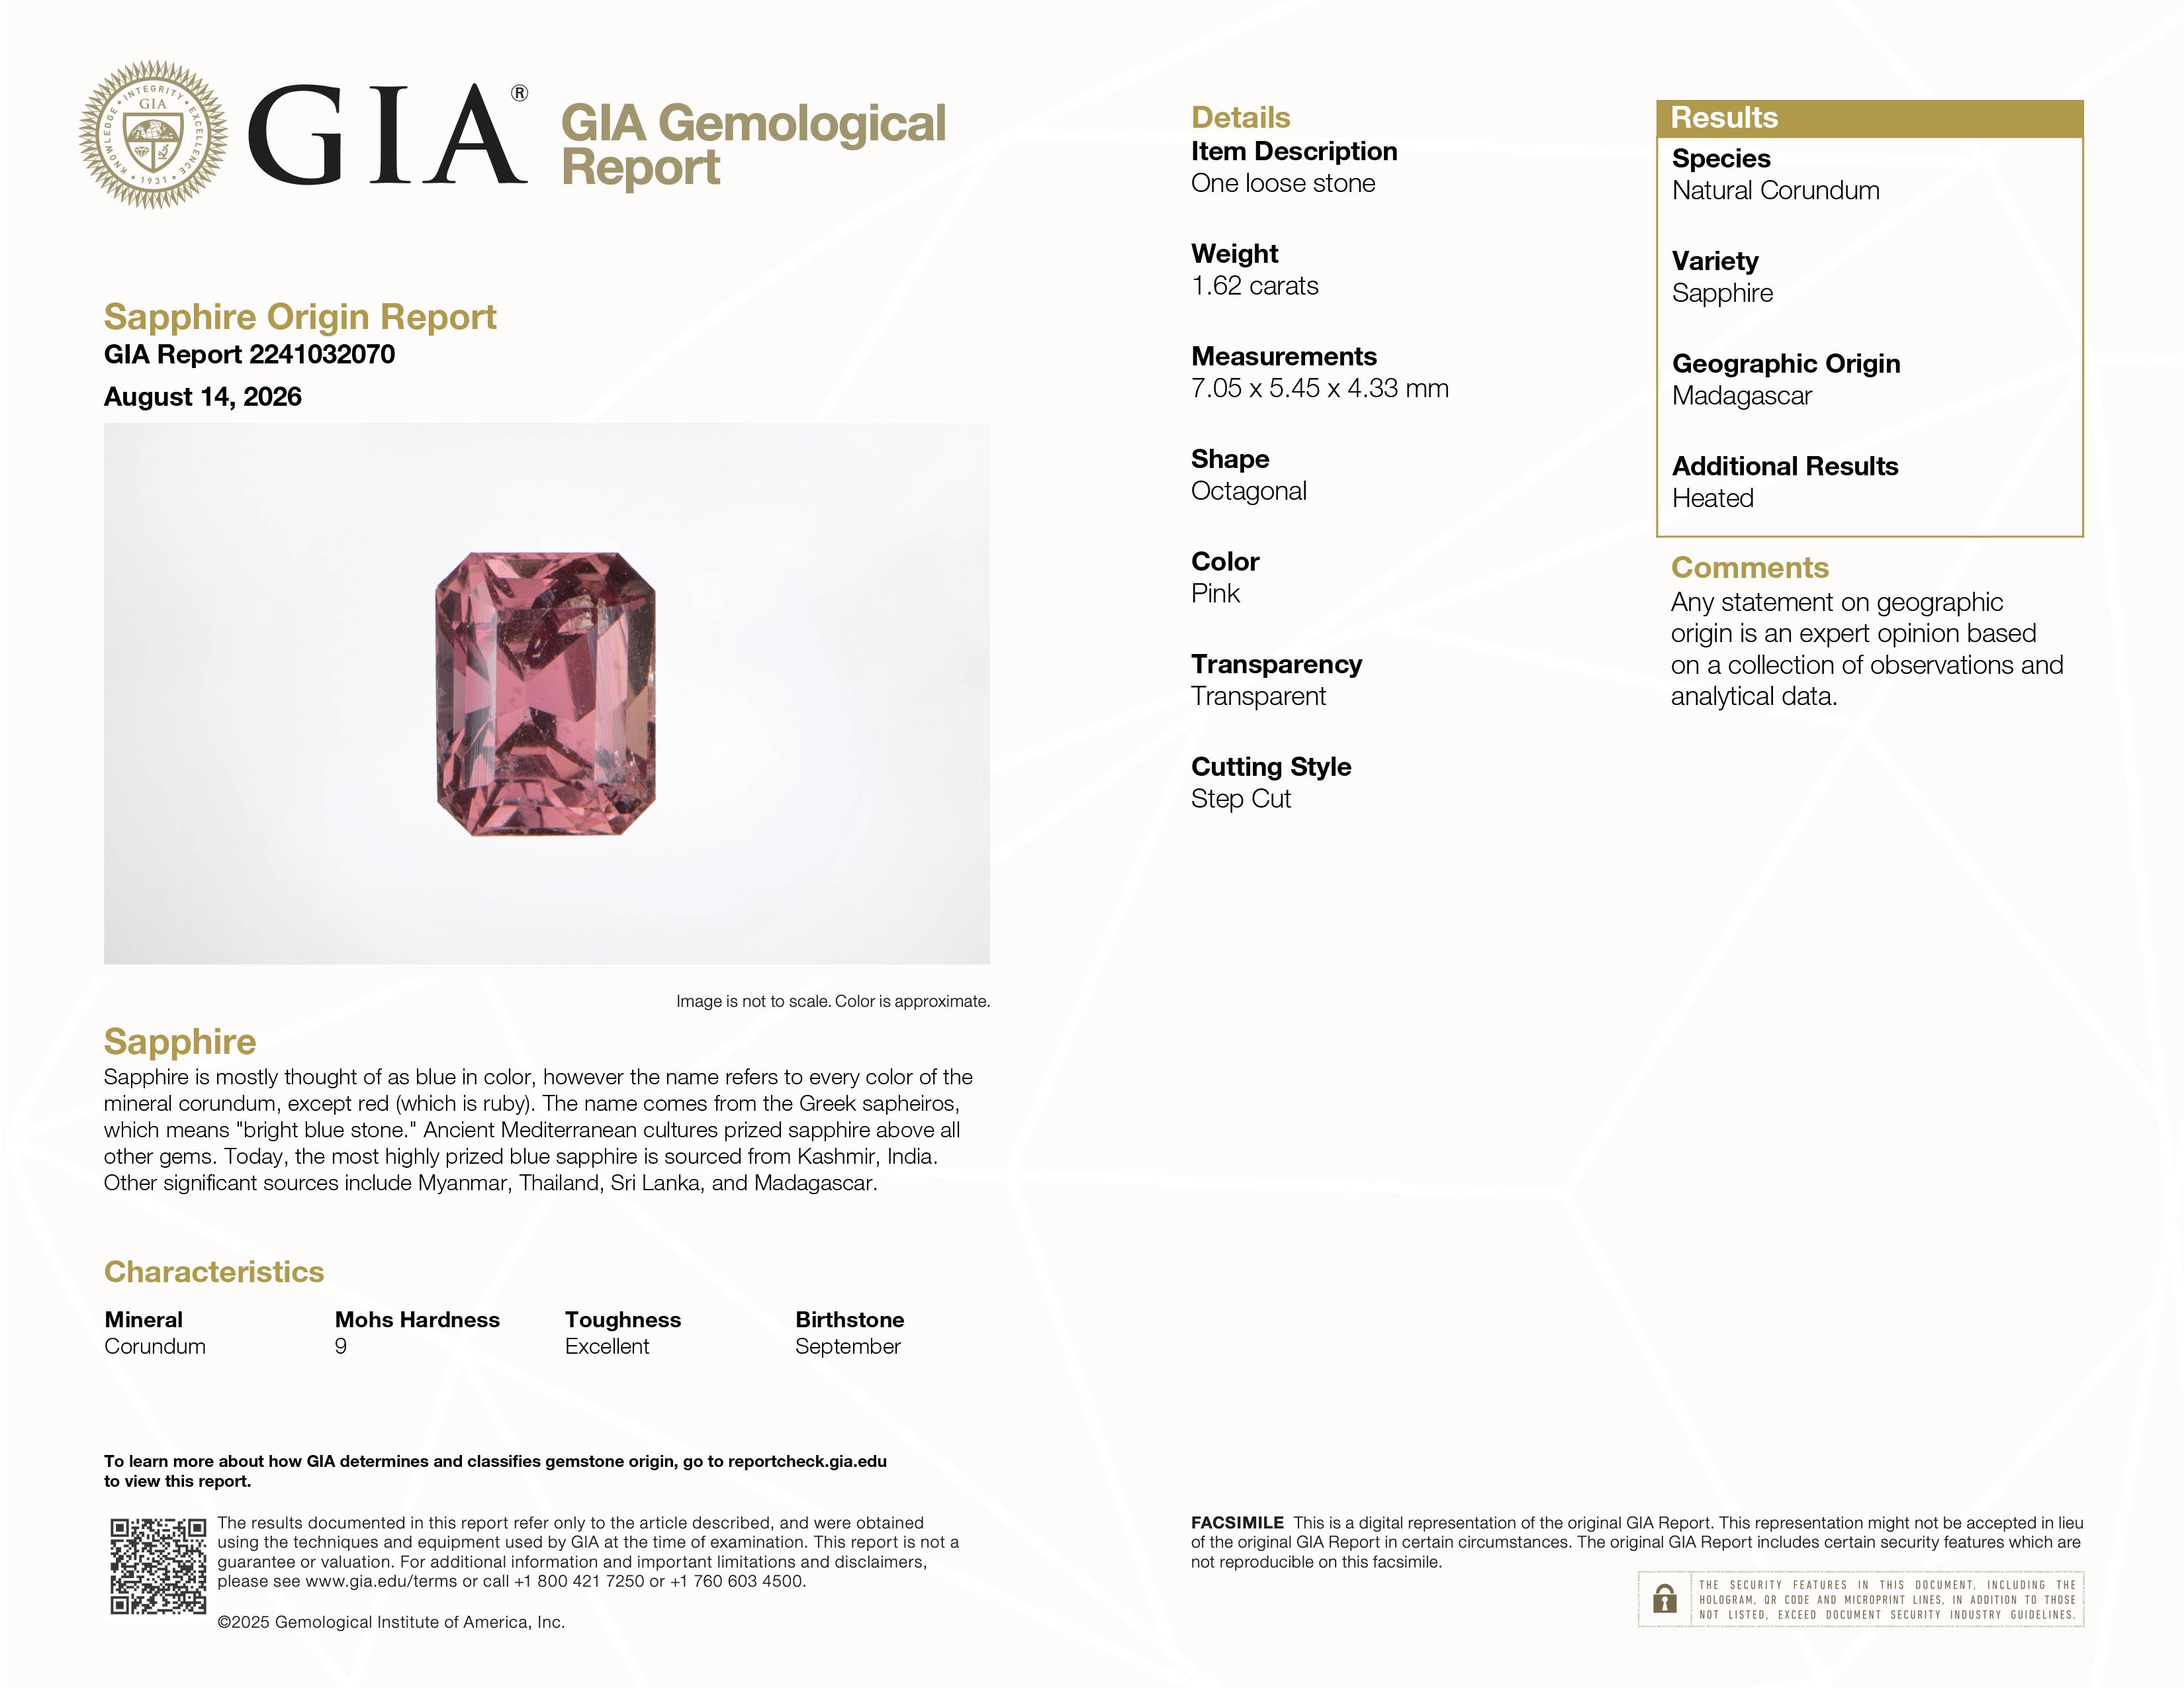
天然ピンクサファイア 1.62ct マダガスカル産【GIA原産地レポート付】エメラルドカット ルース
CG8460
CG8459
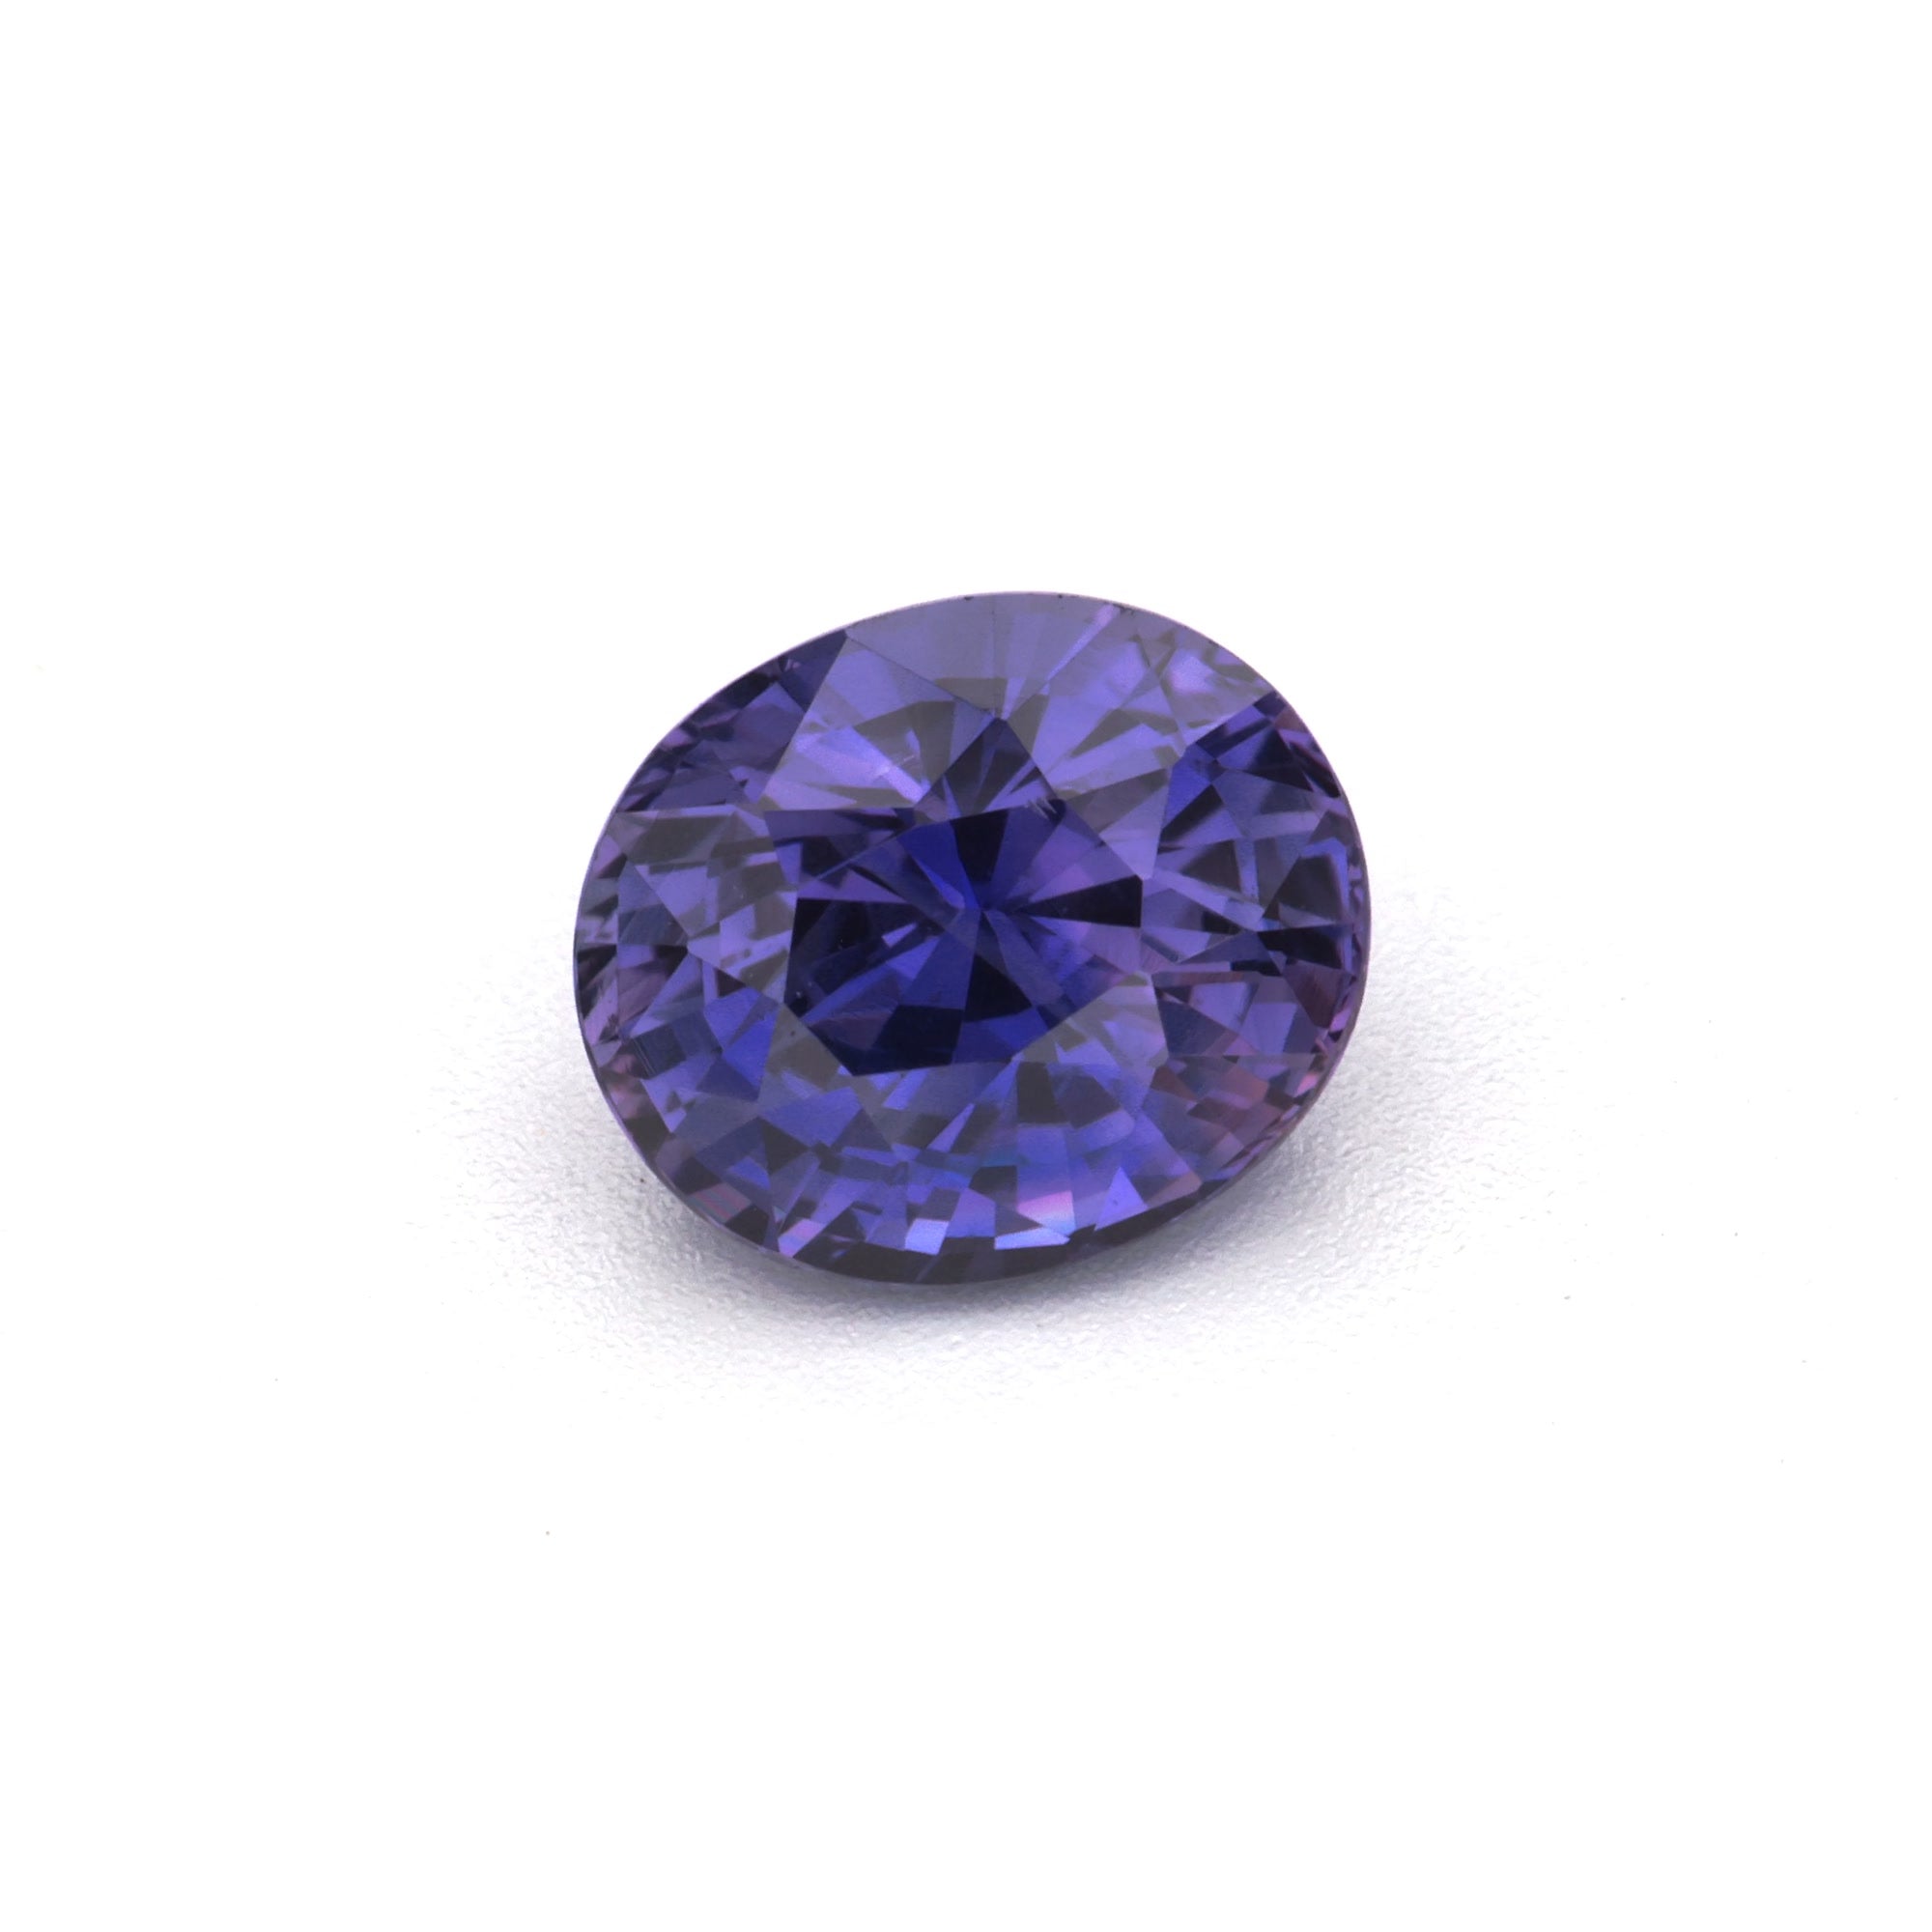
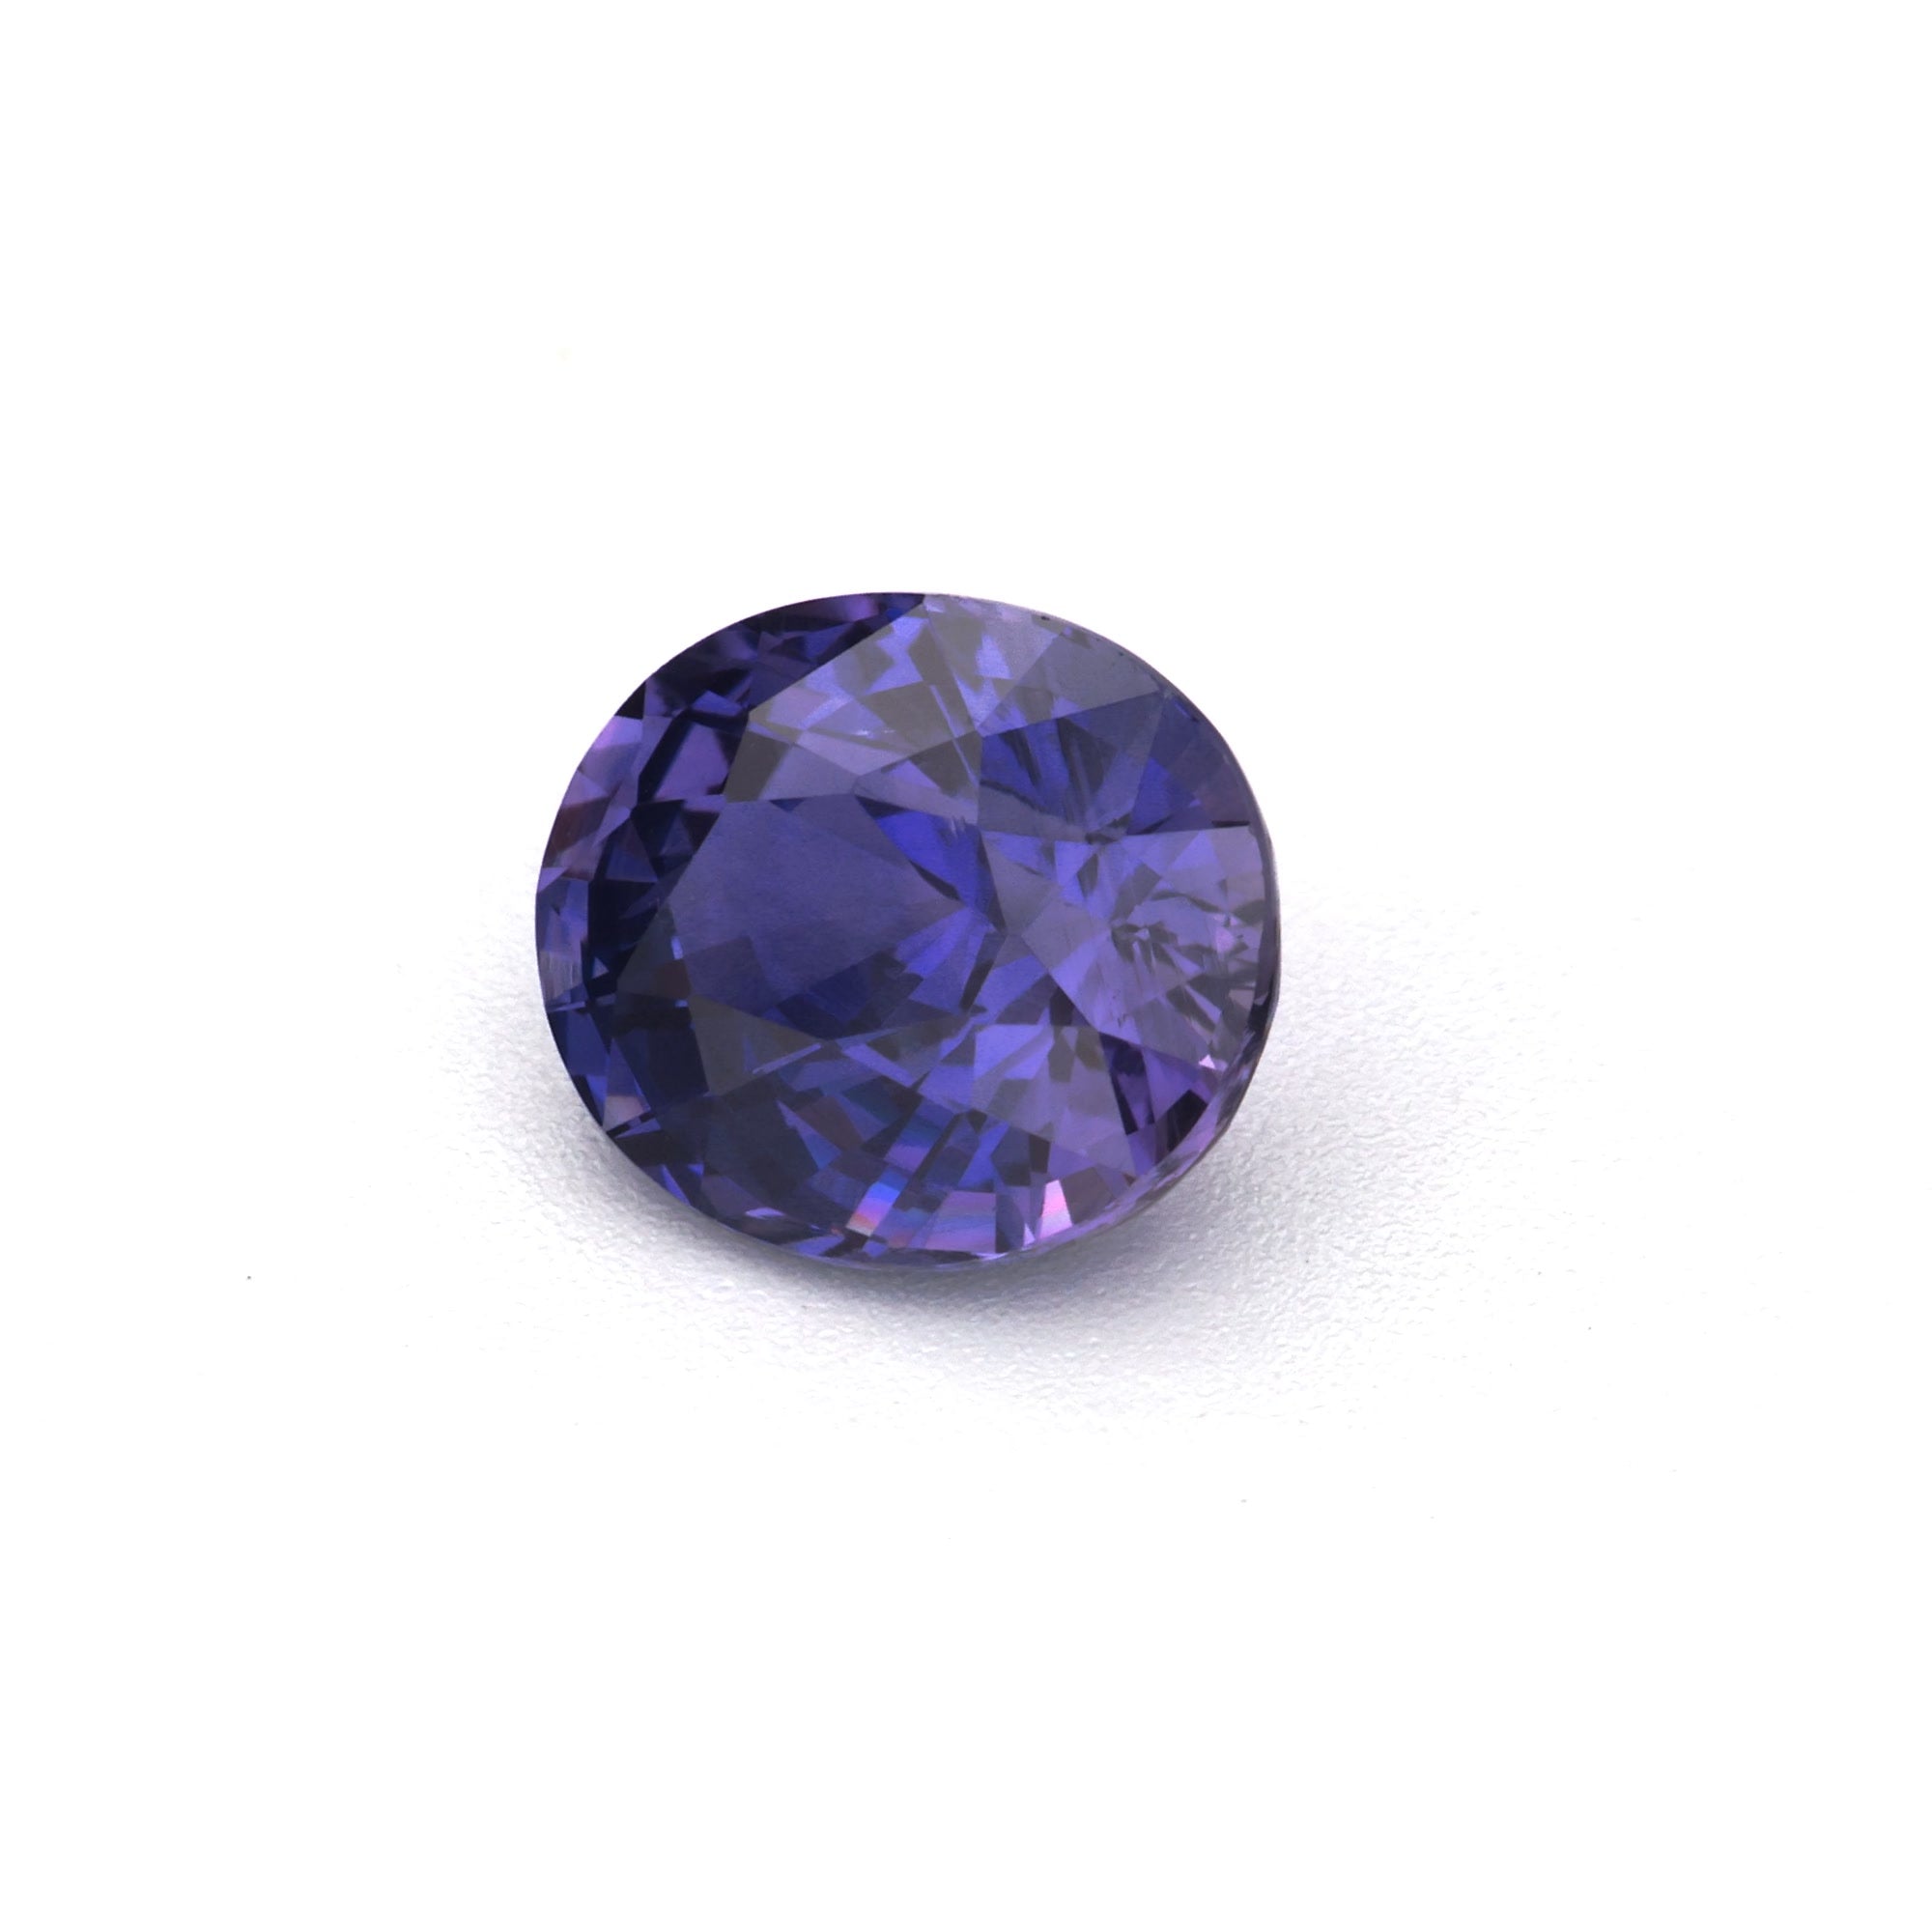
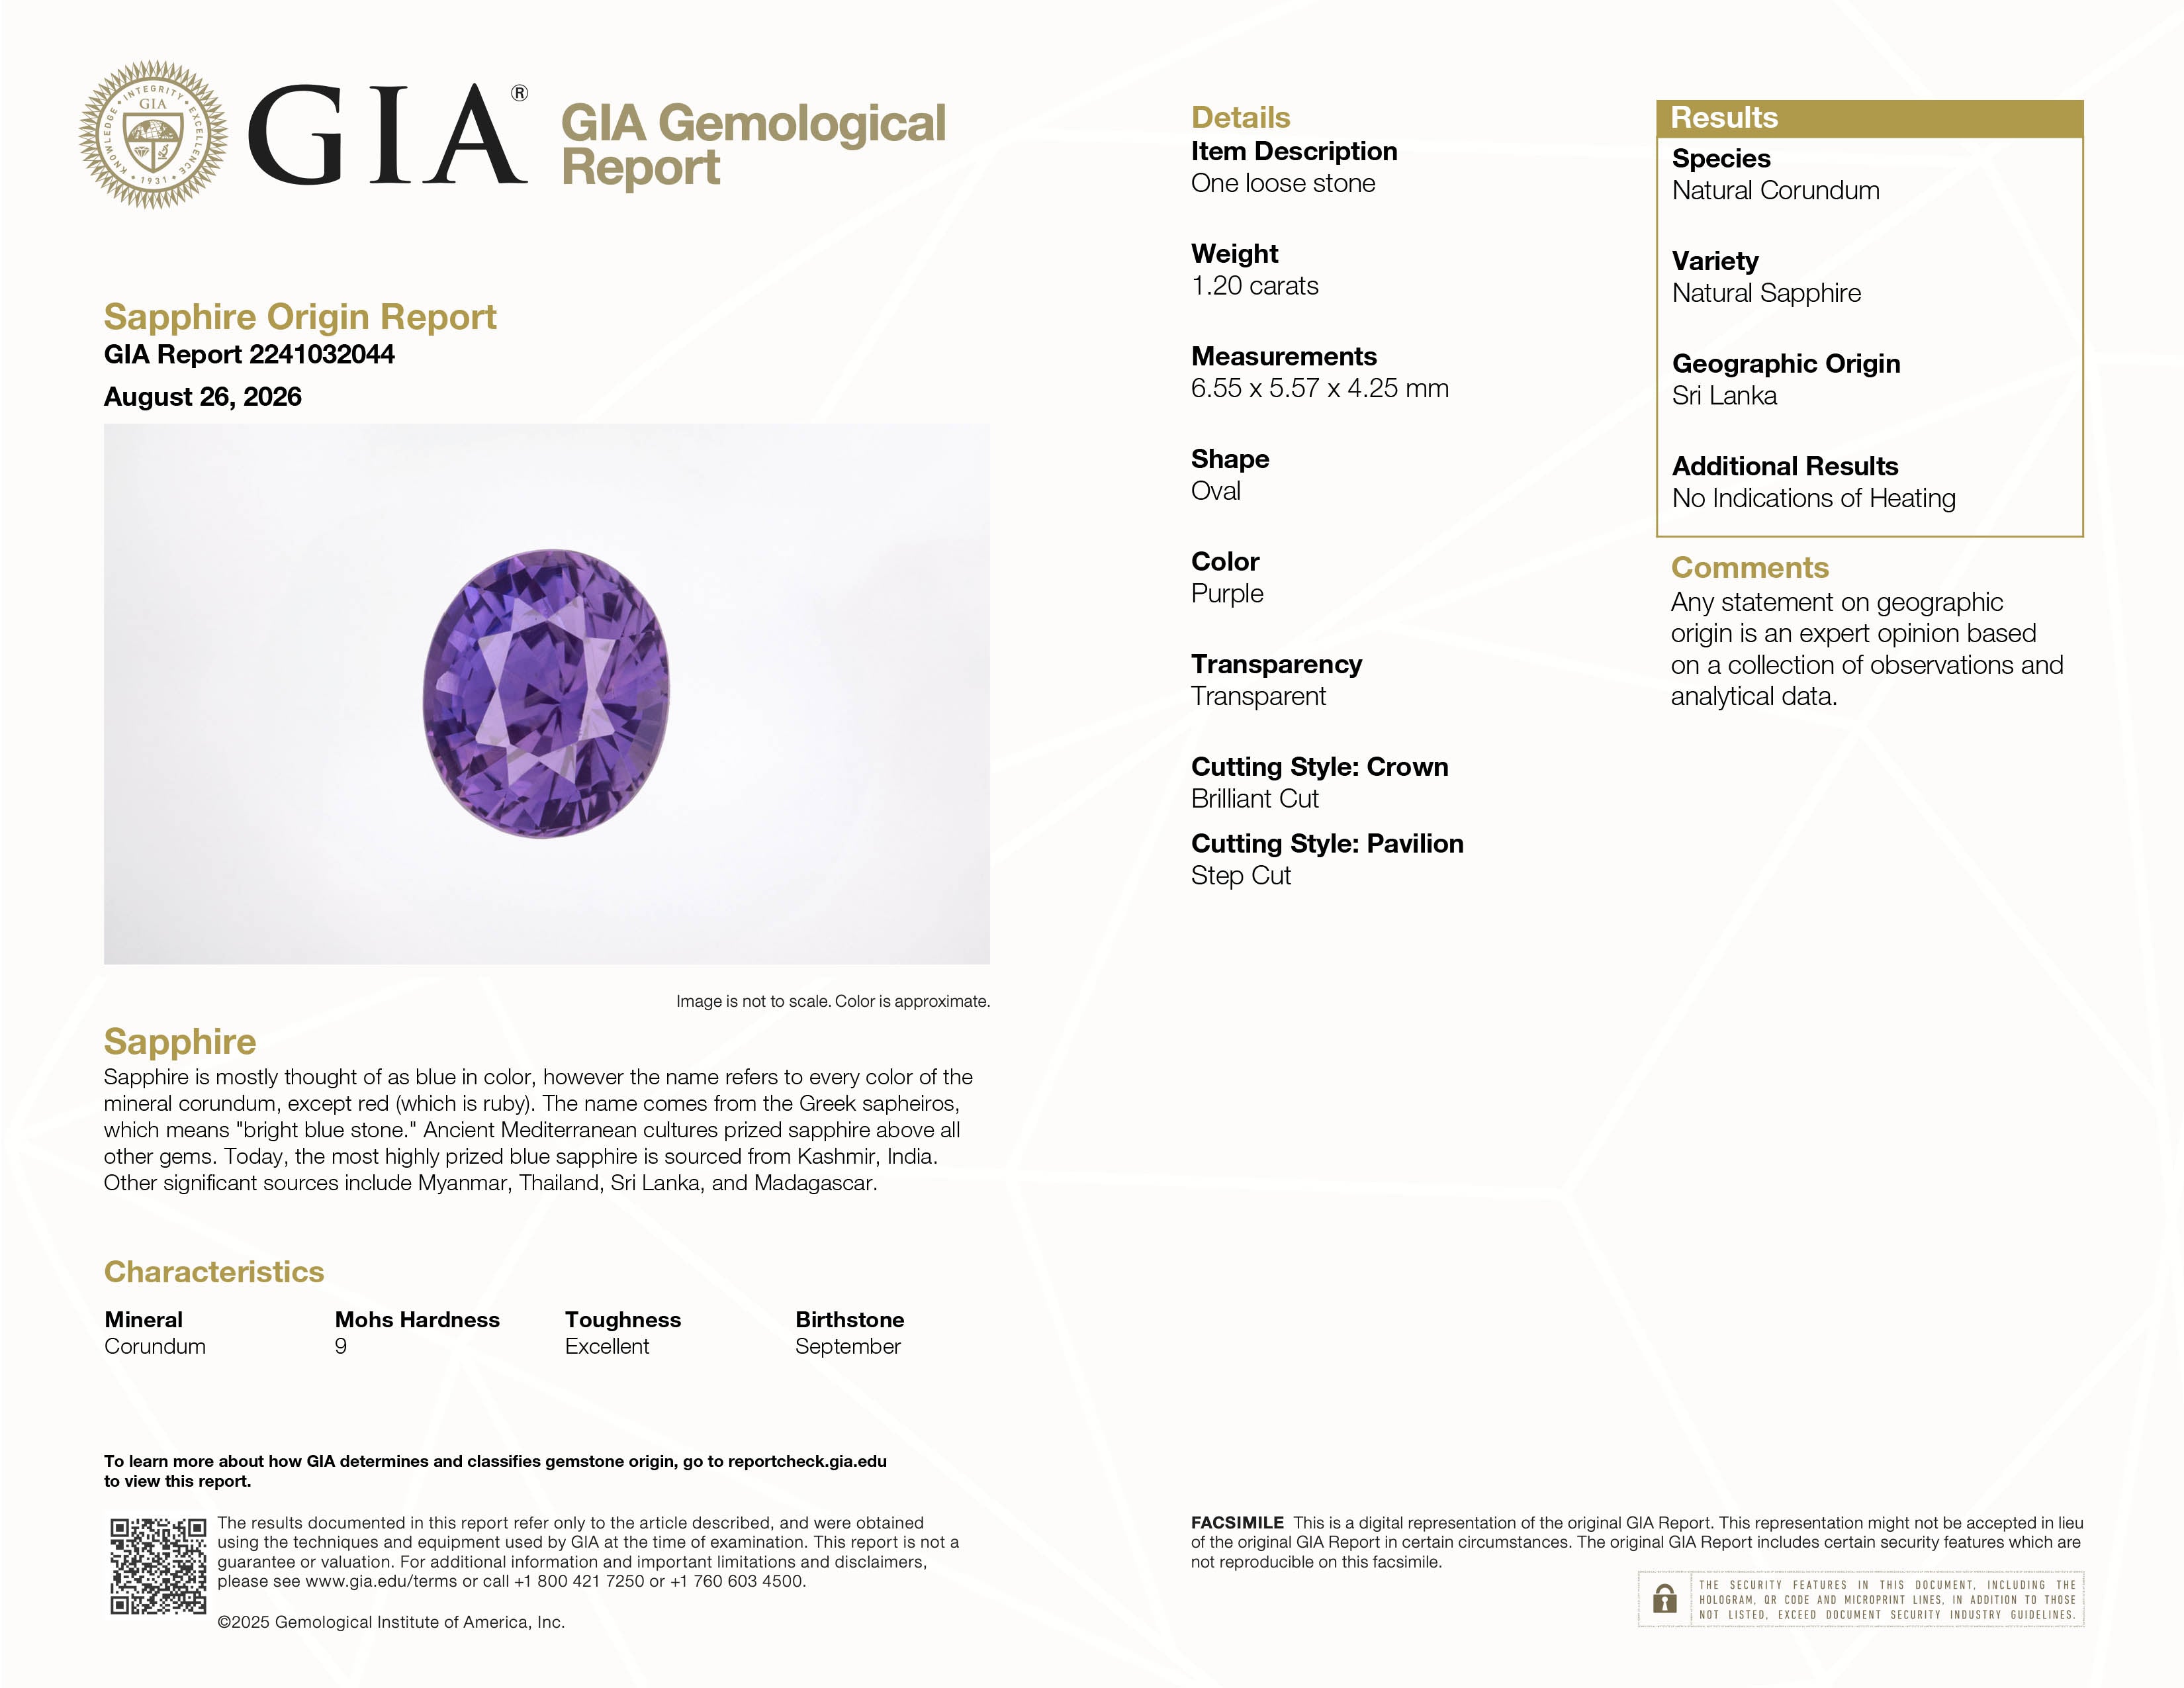
パープルサファイア 1.20ct 非加熱|スリランカ産|GIA原産地レポート付きルース
CG8458
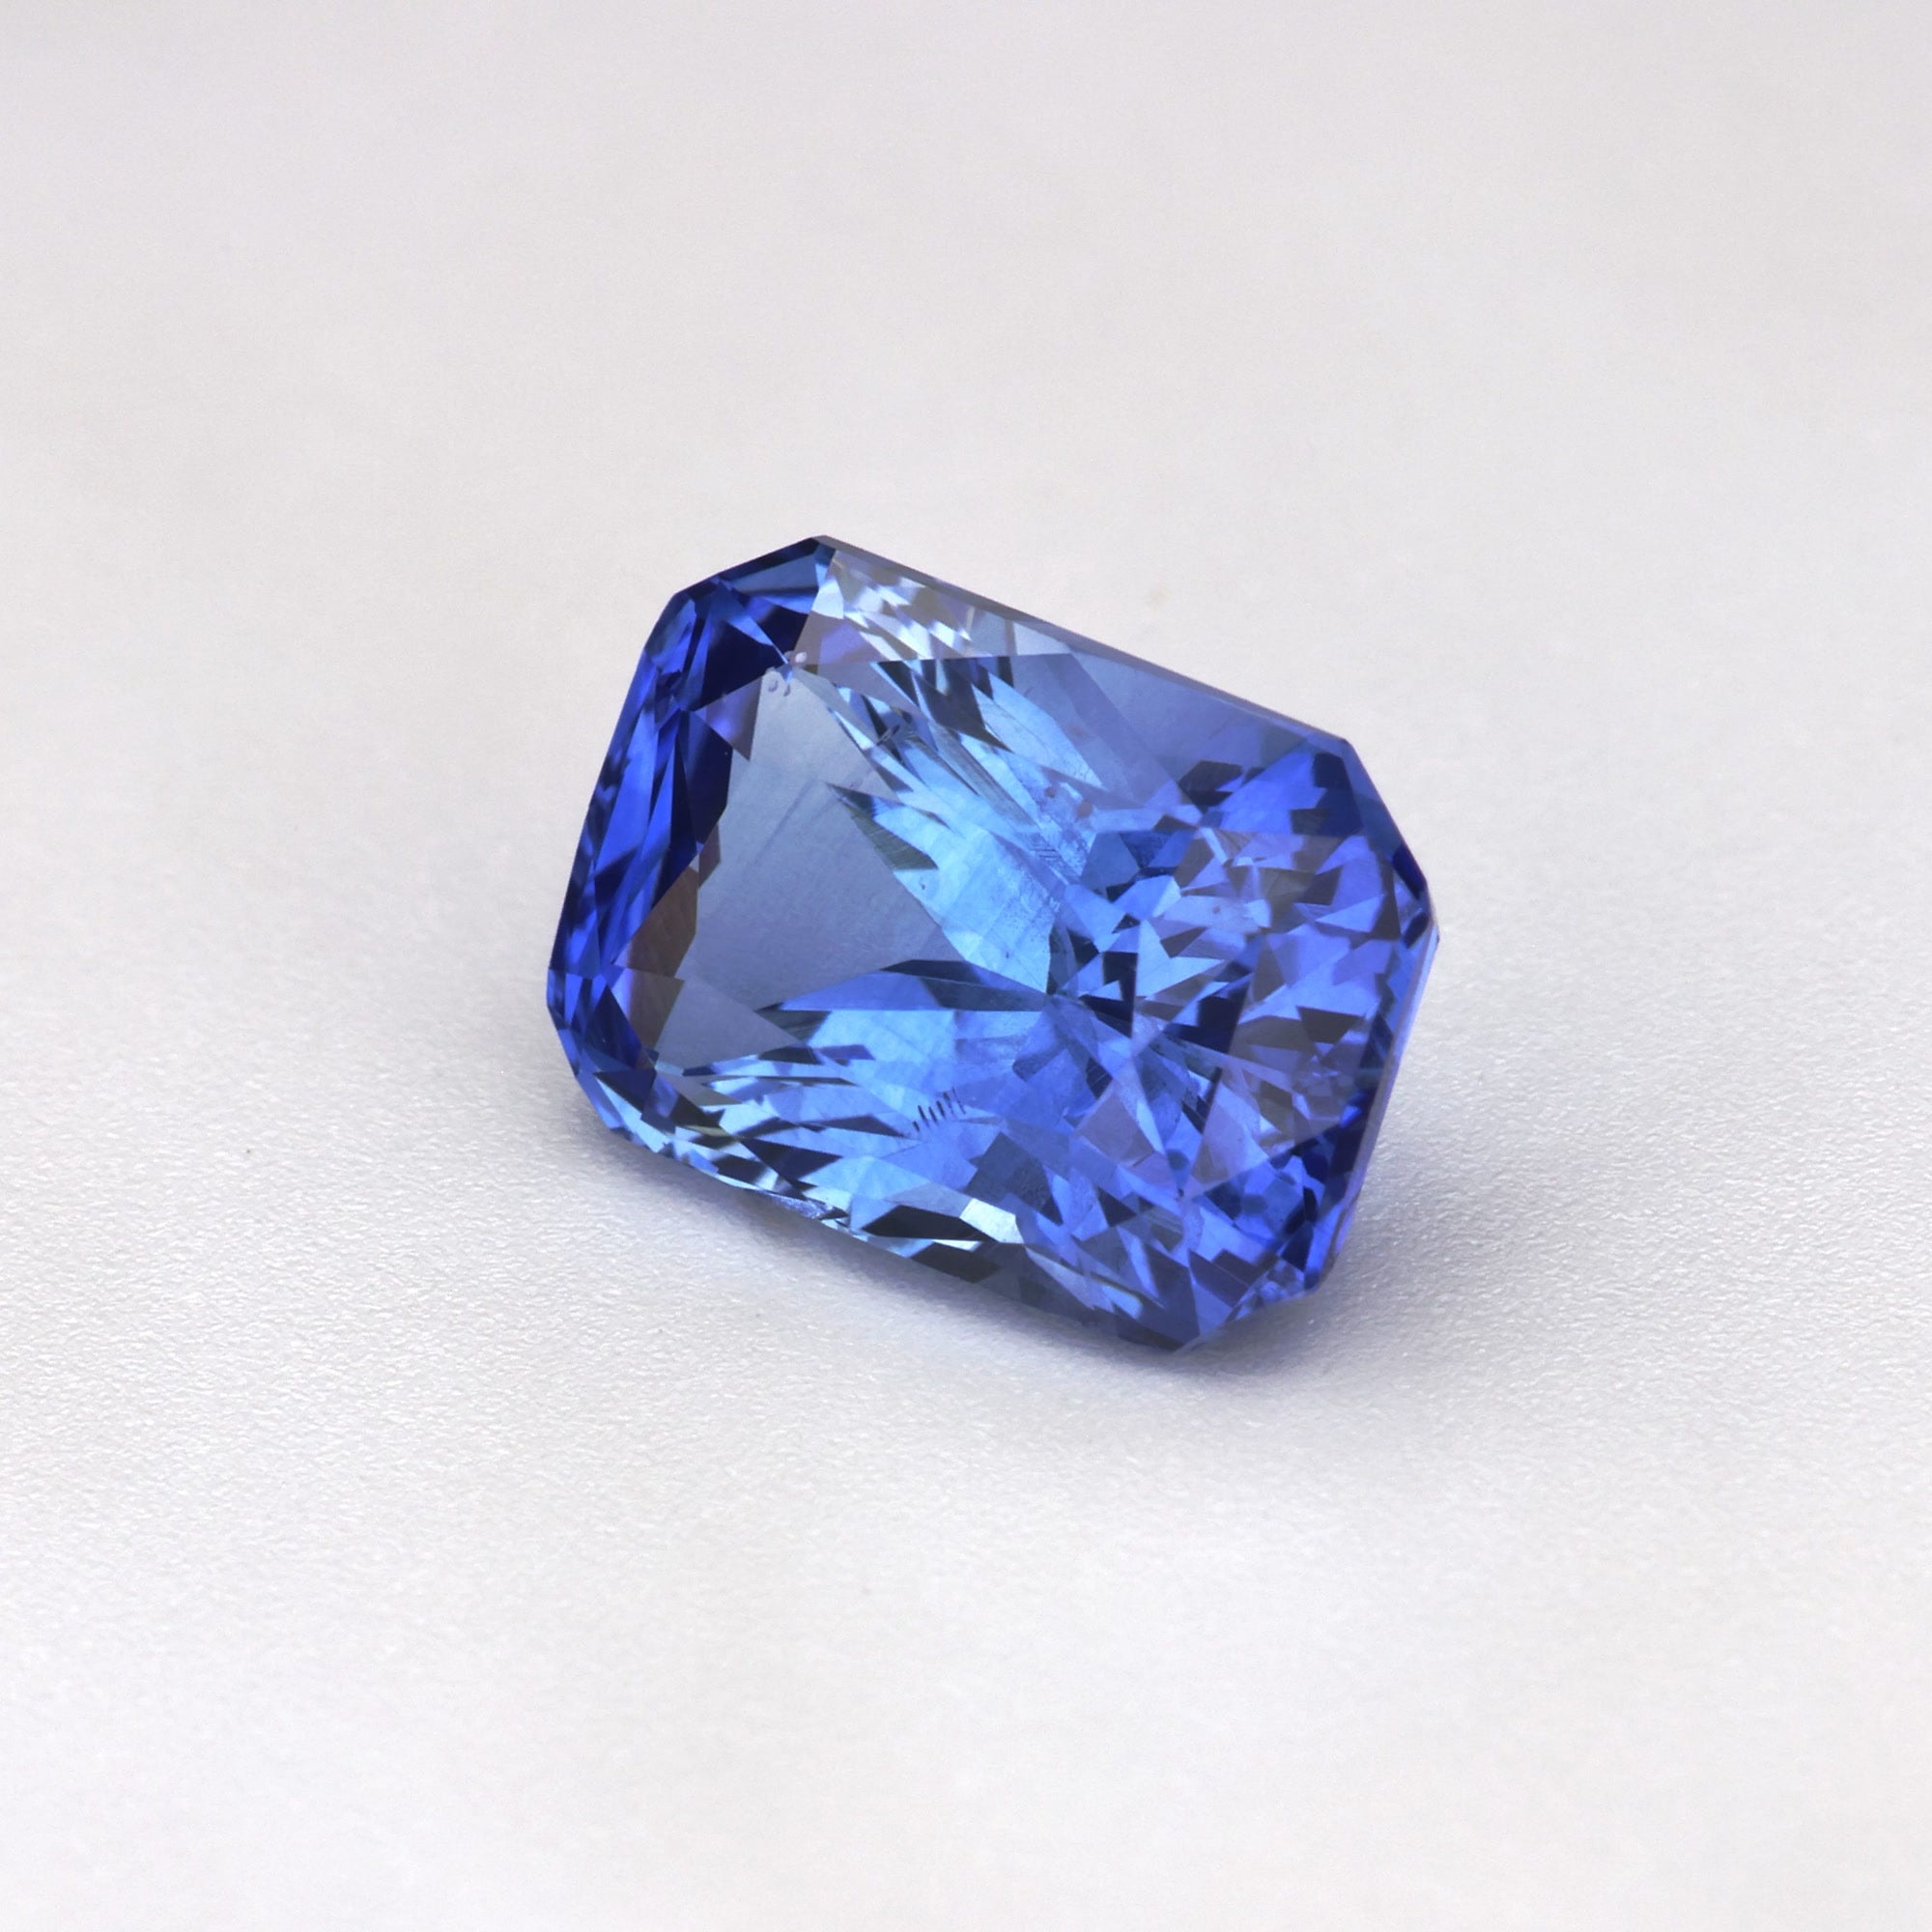
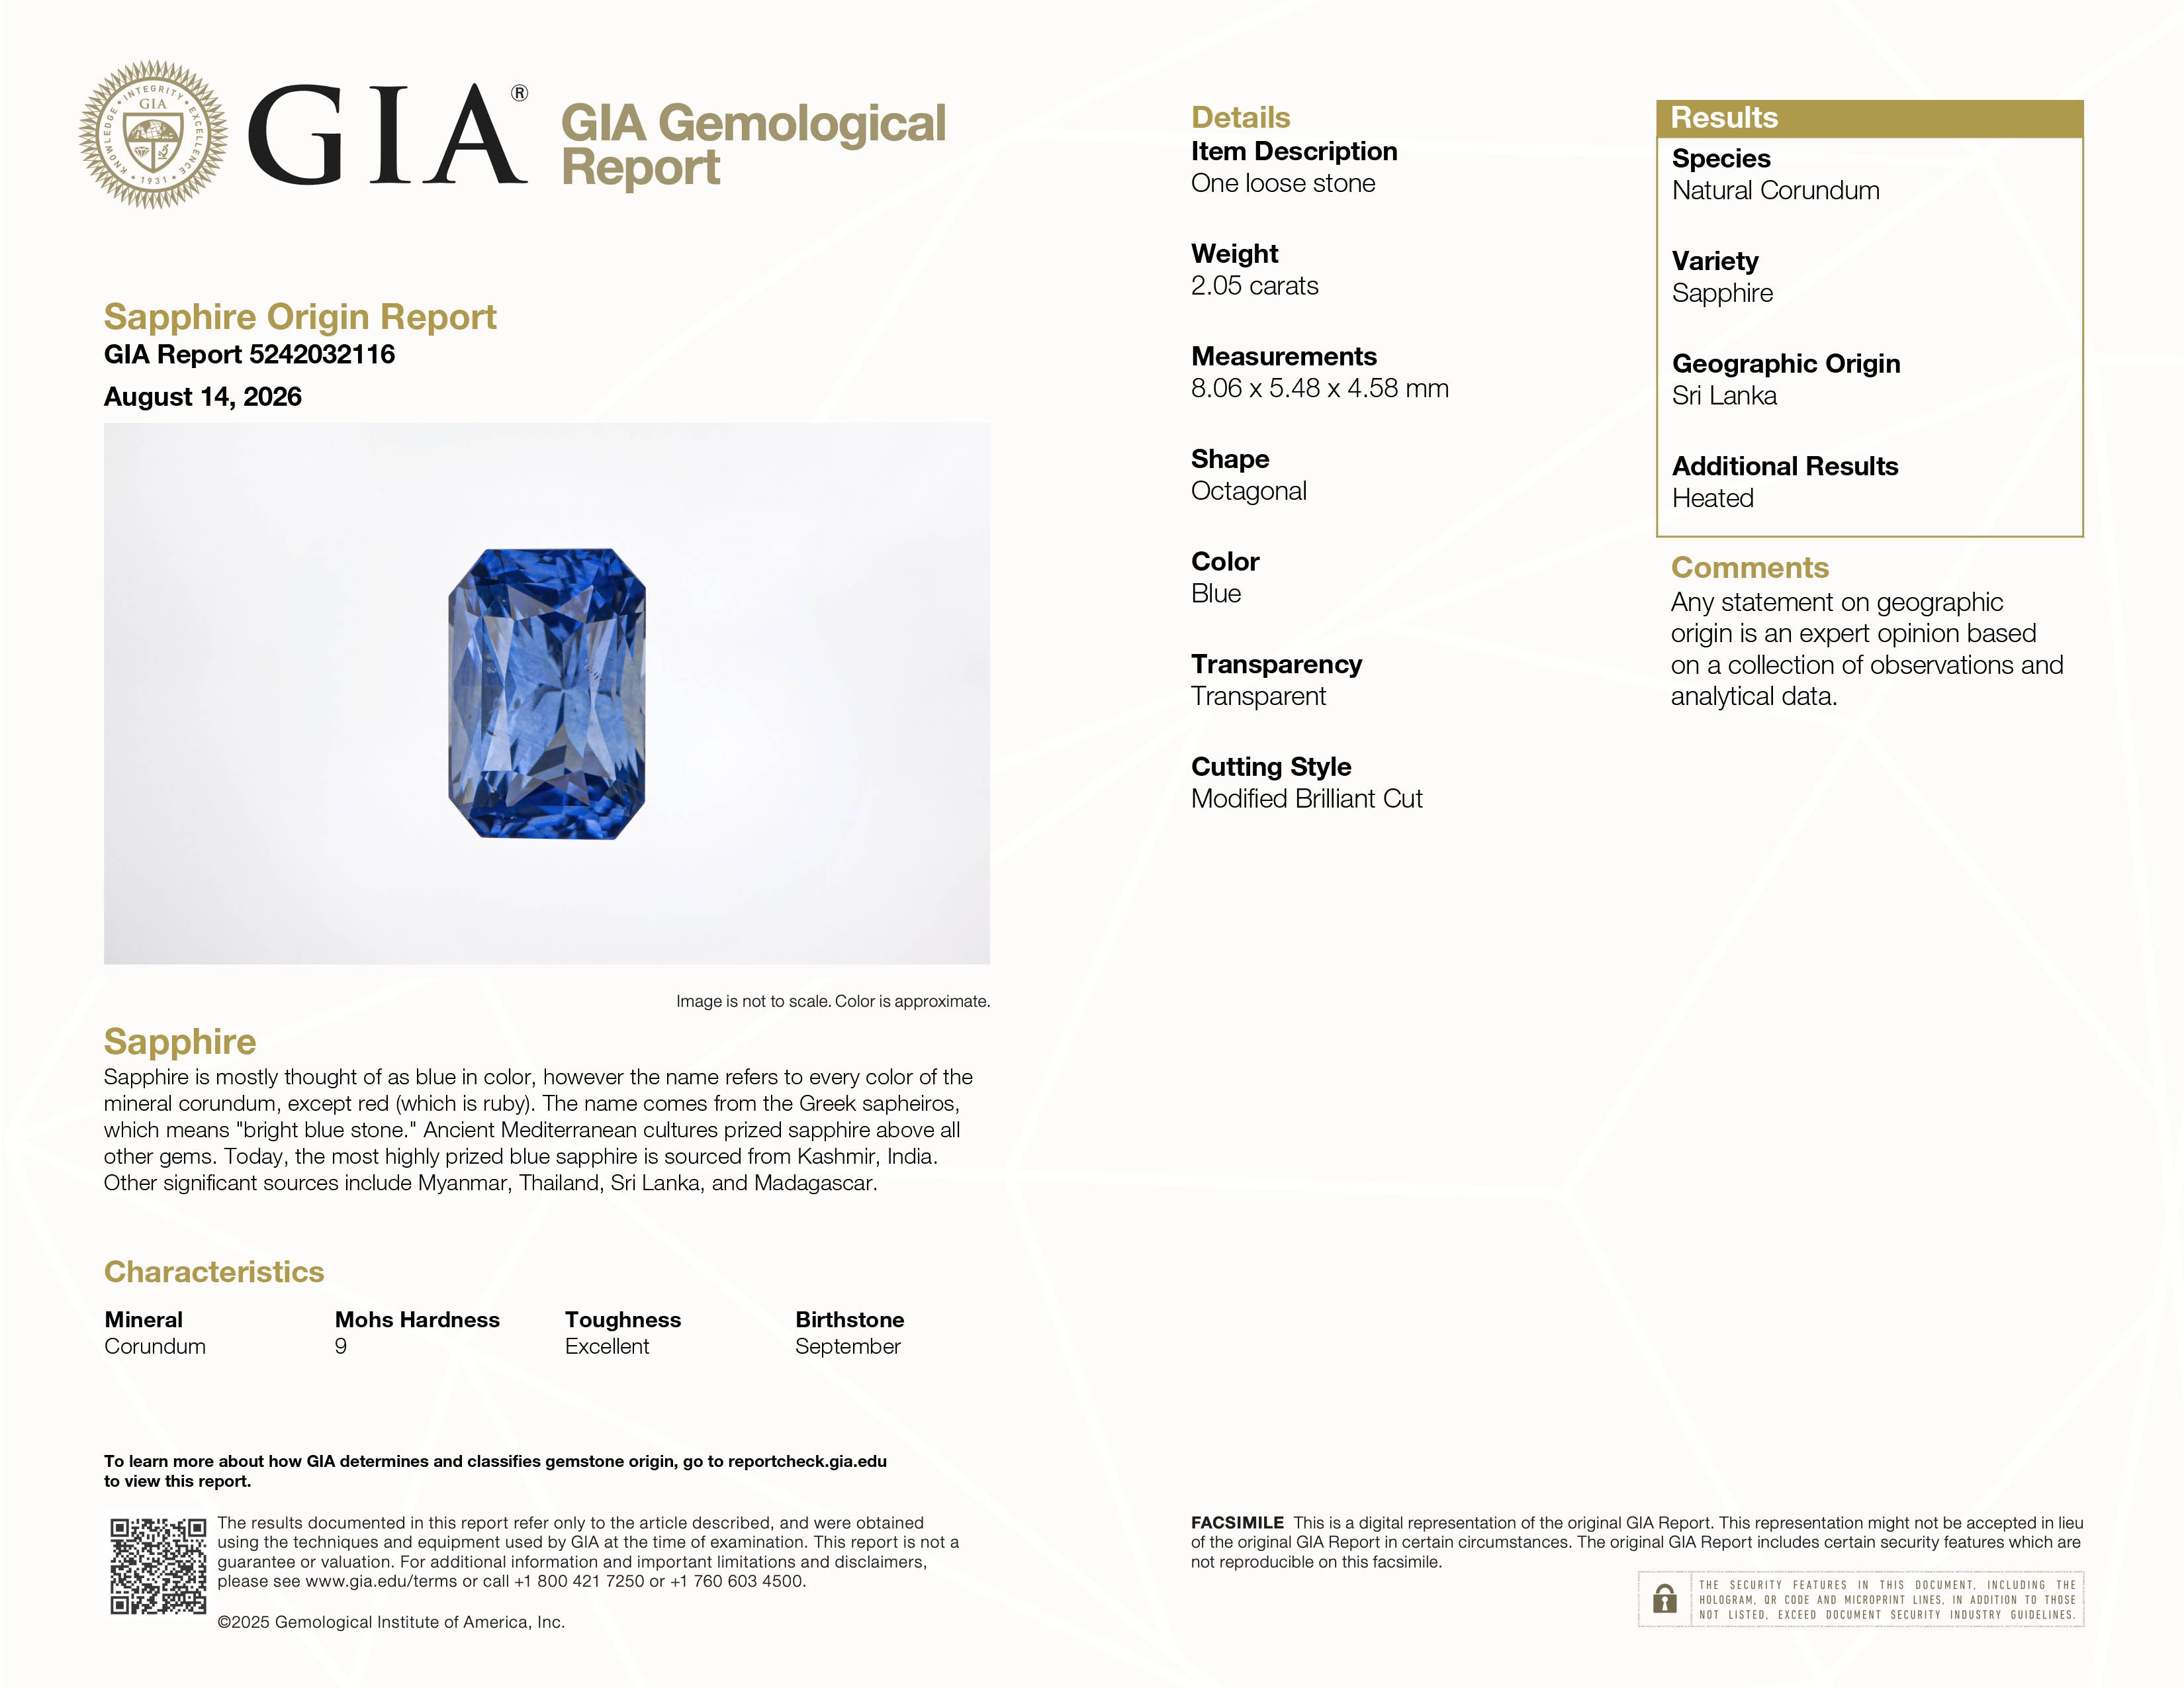
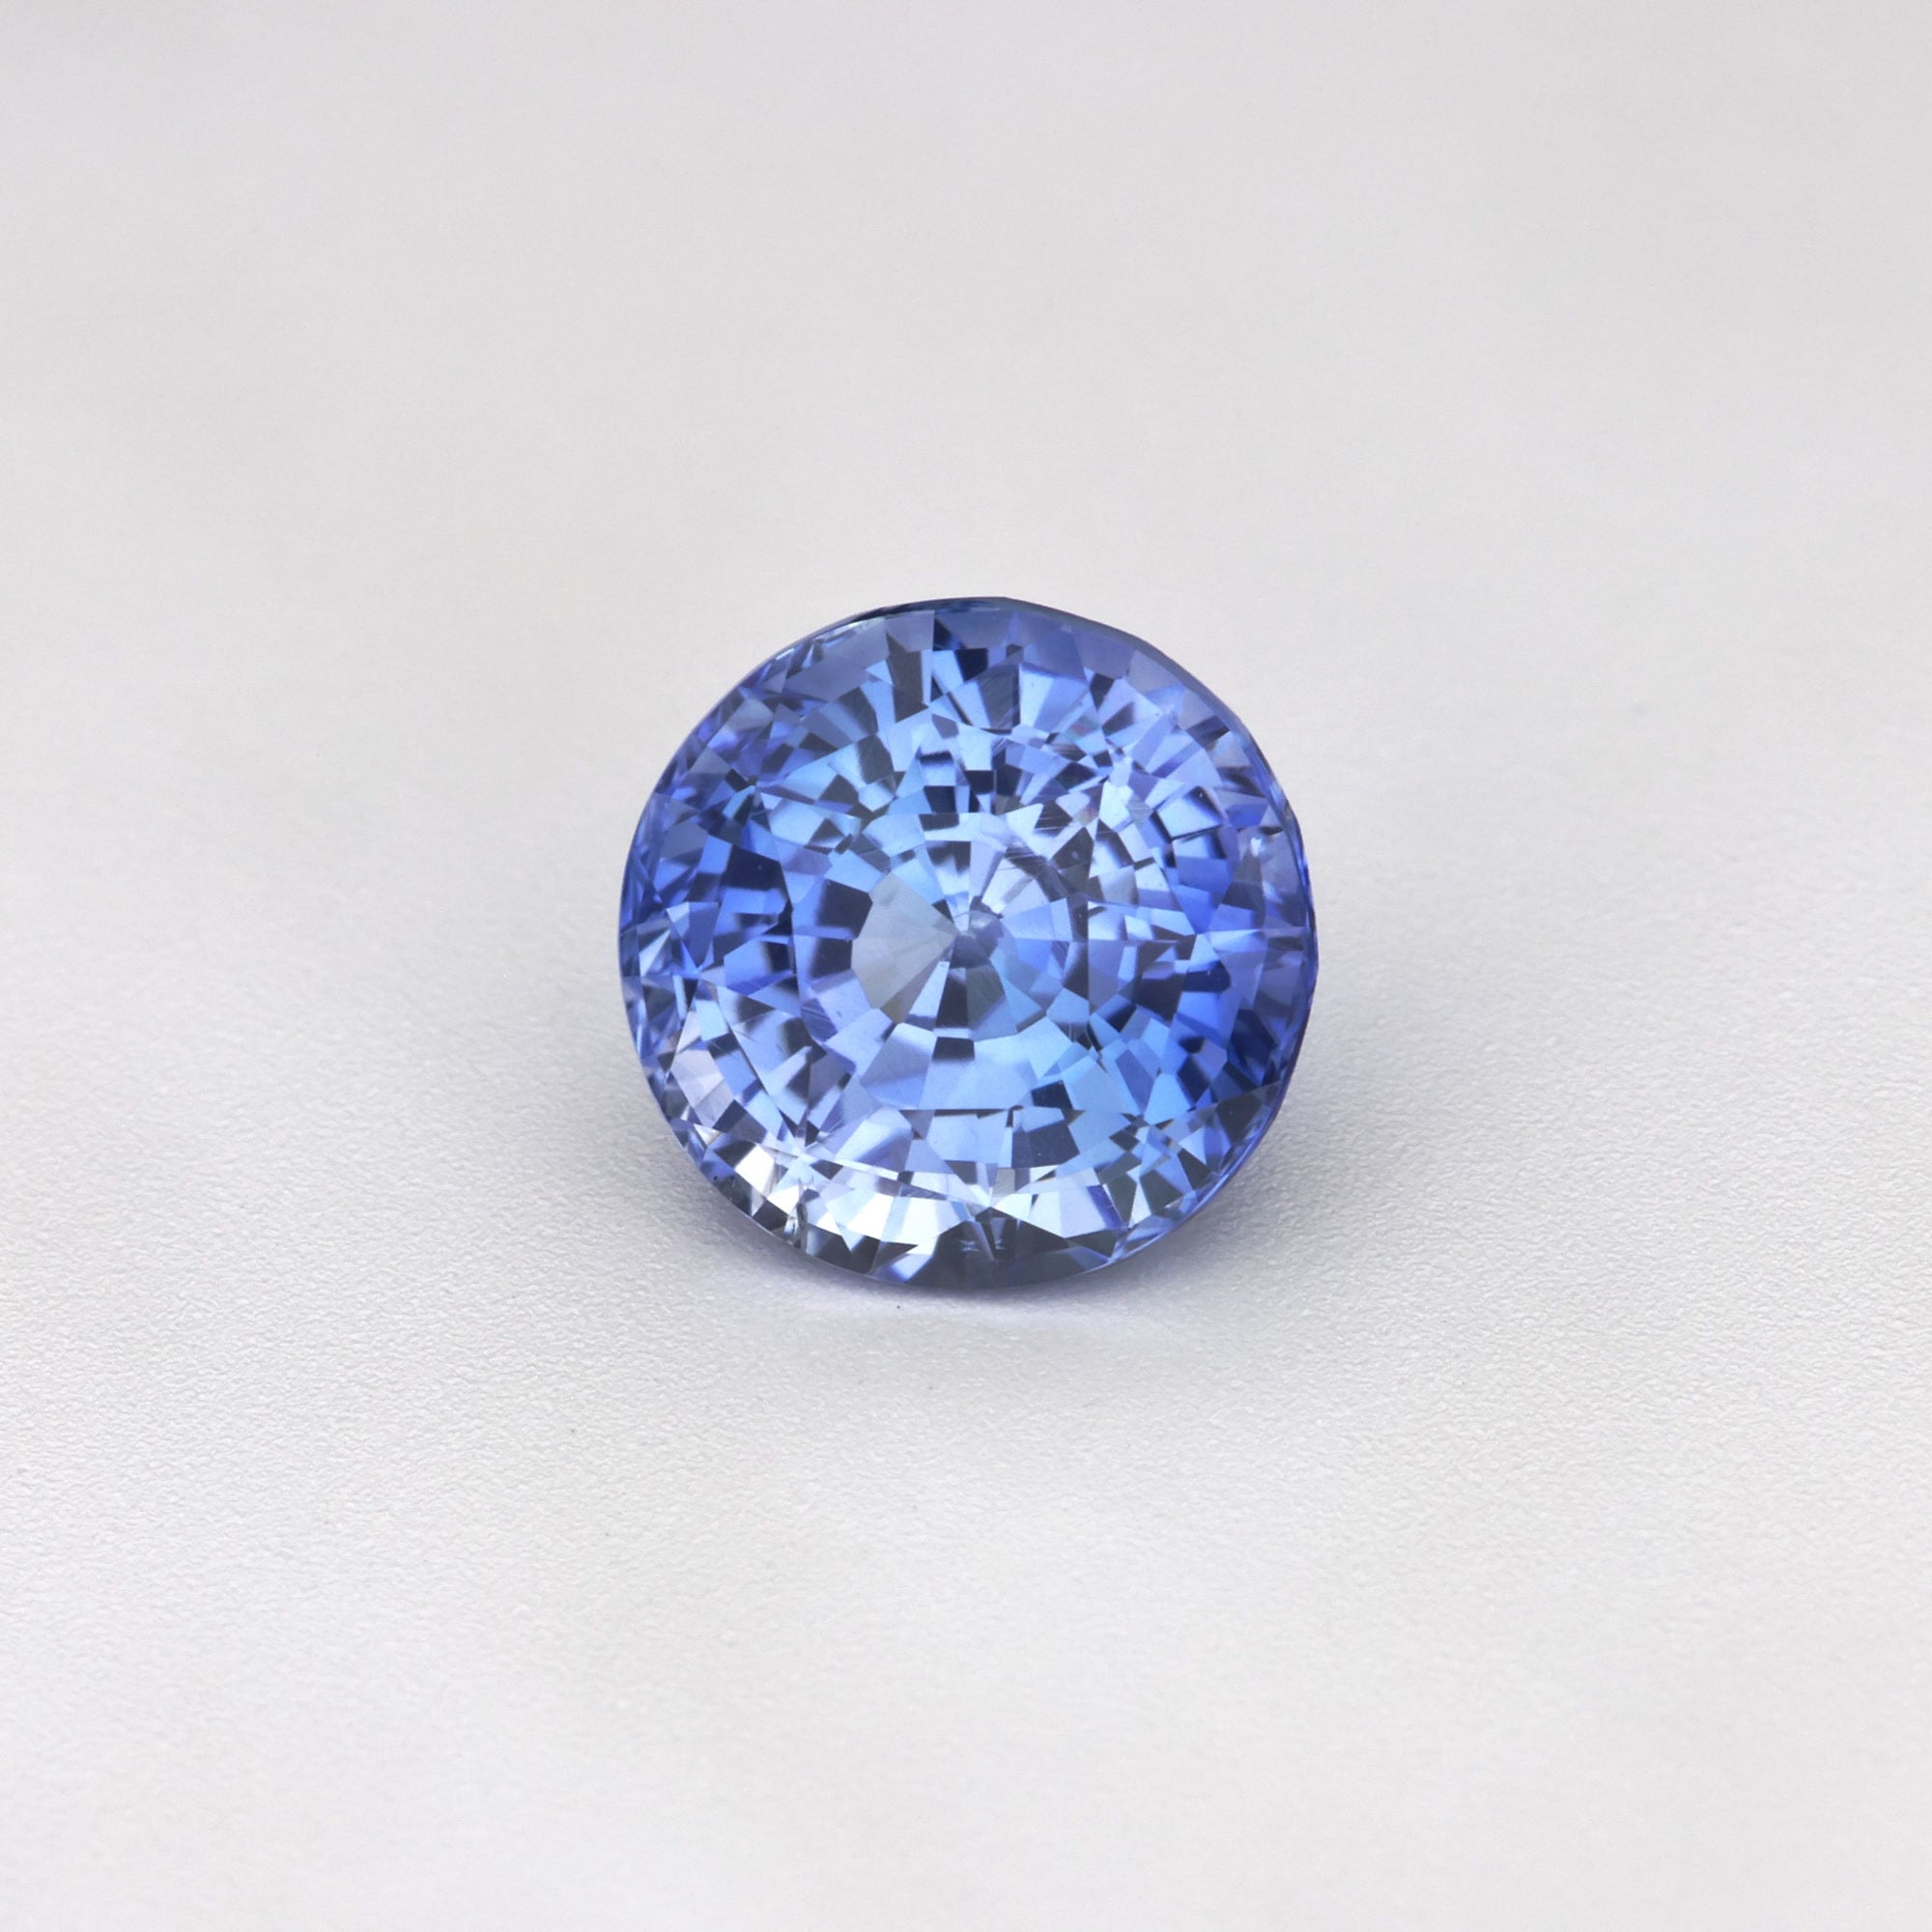
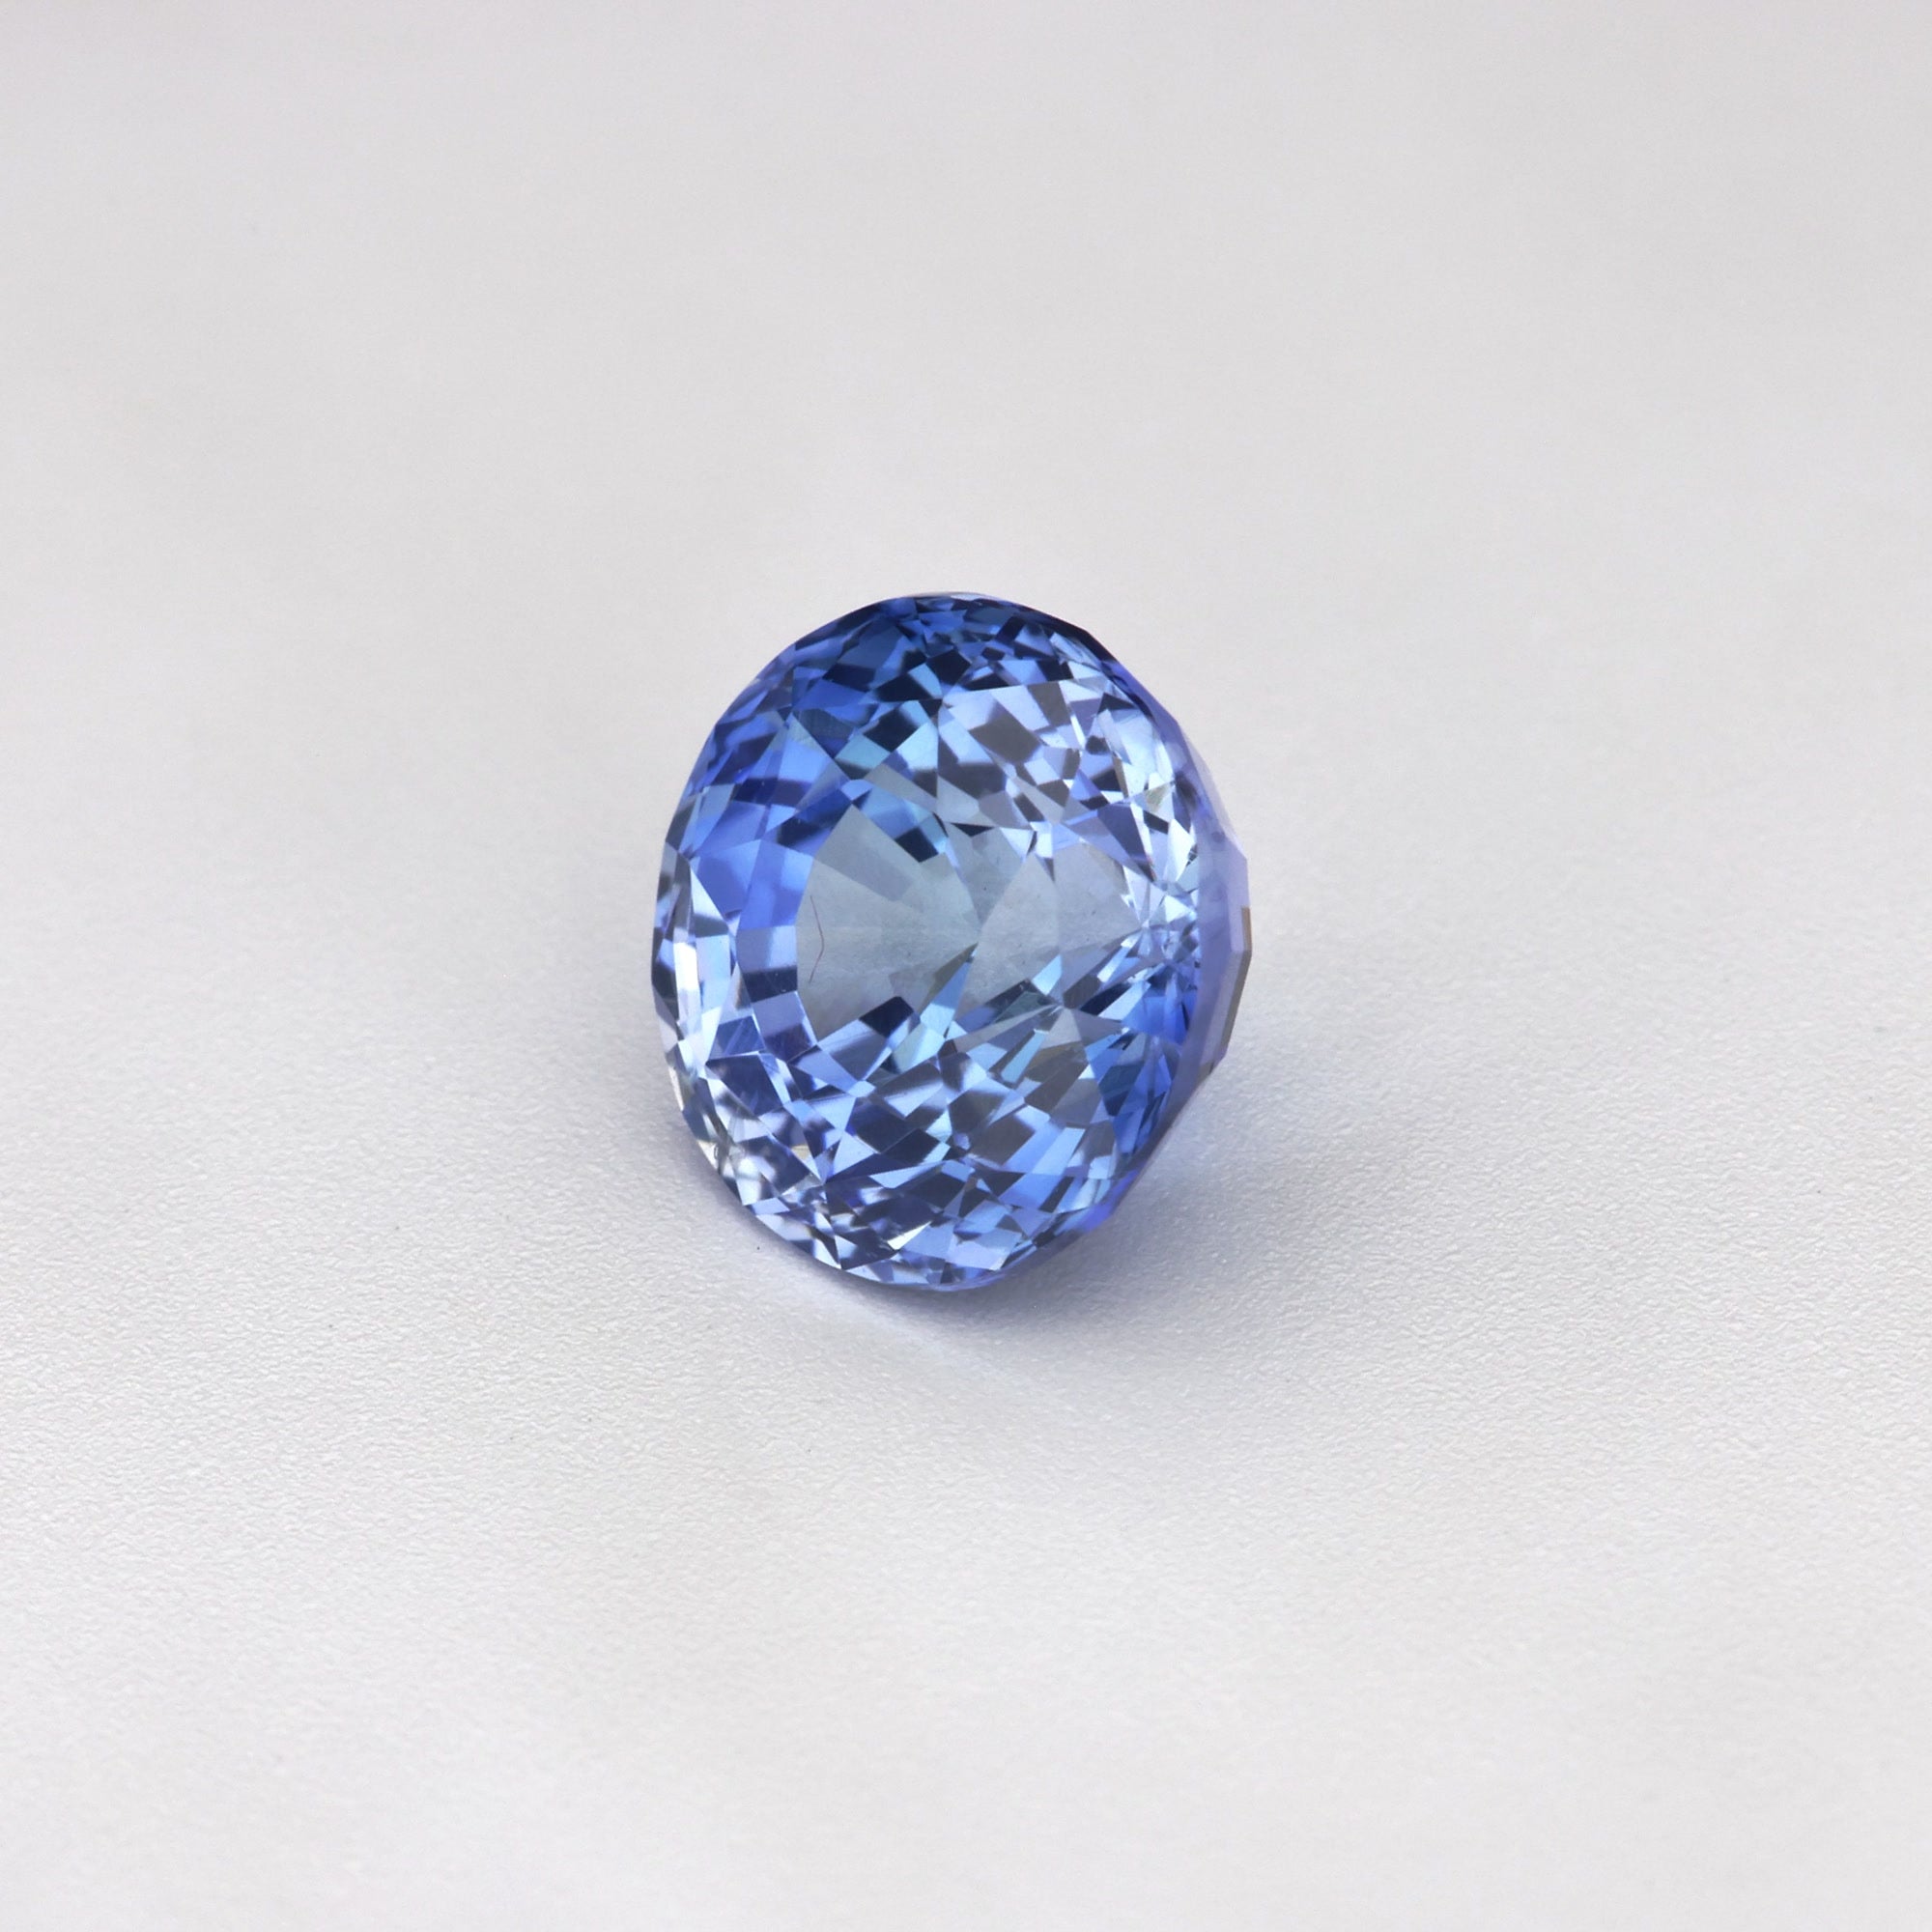
2.05ct 加熱ブルーサファイア|産地:スリランカ(GIAの意見)|ルース・GIA原産地レポート付き
CG8457
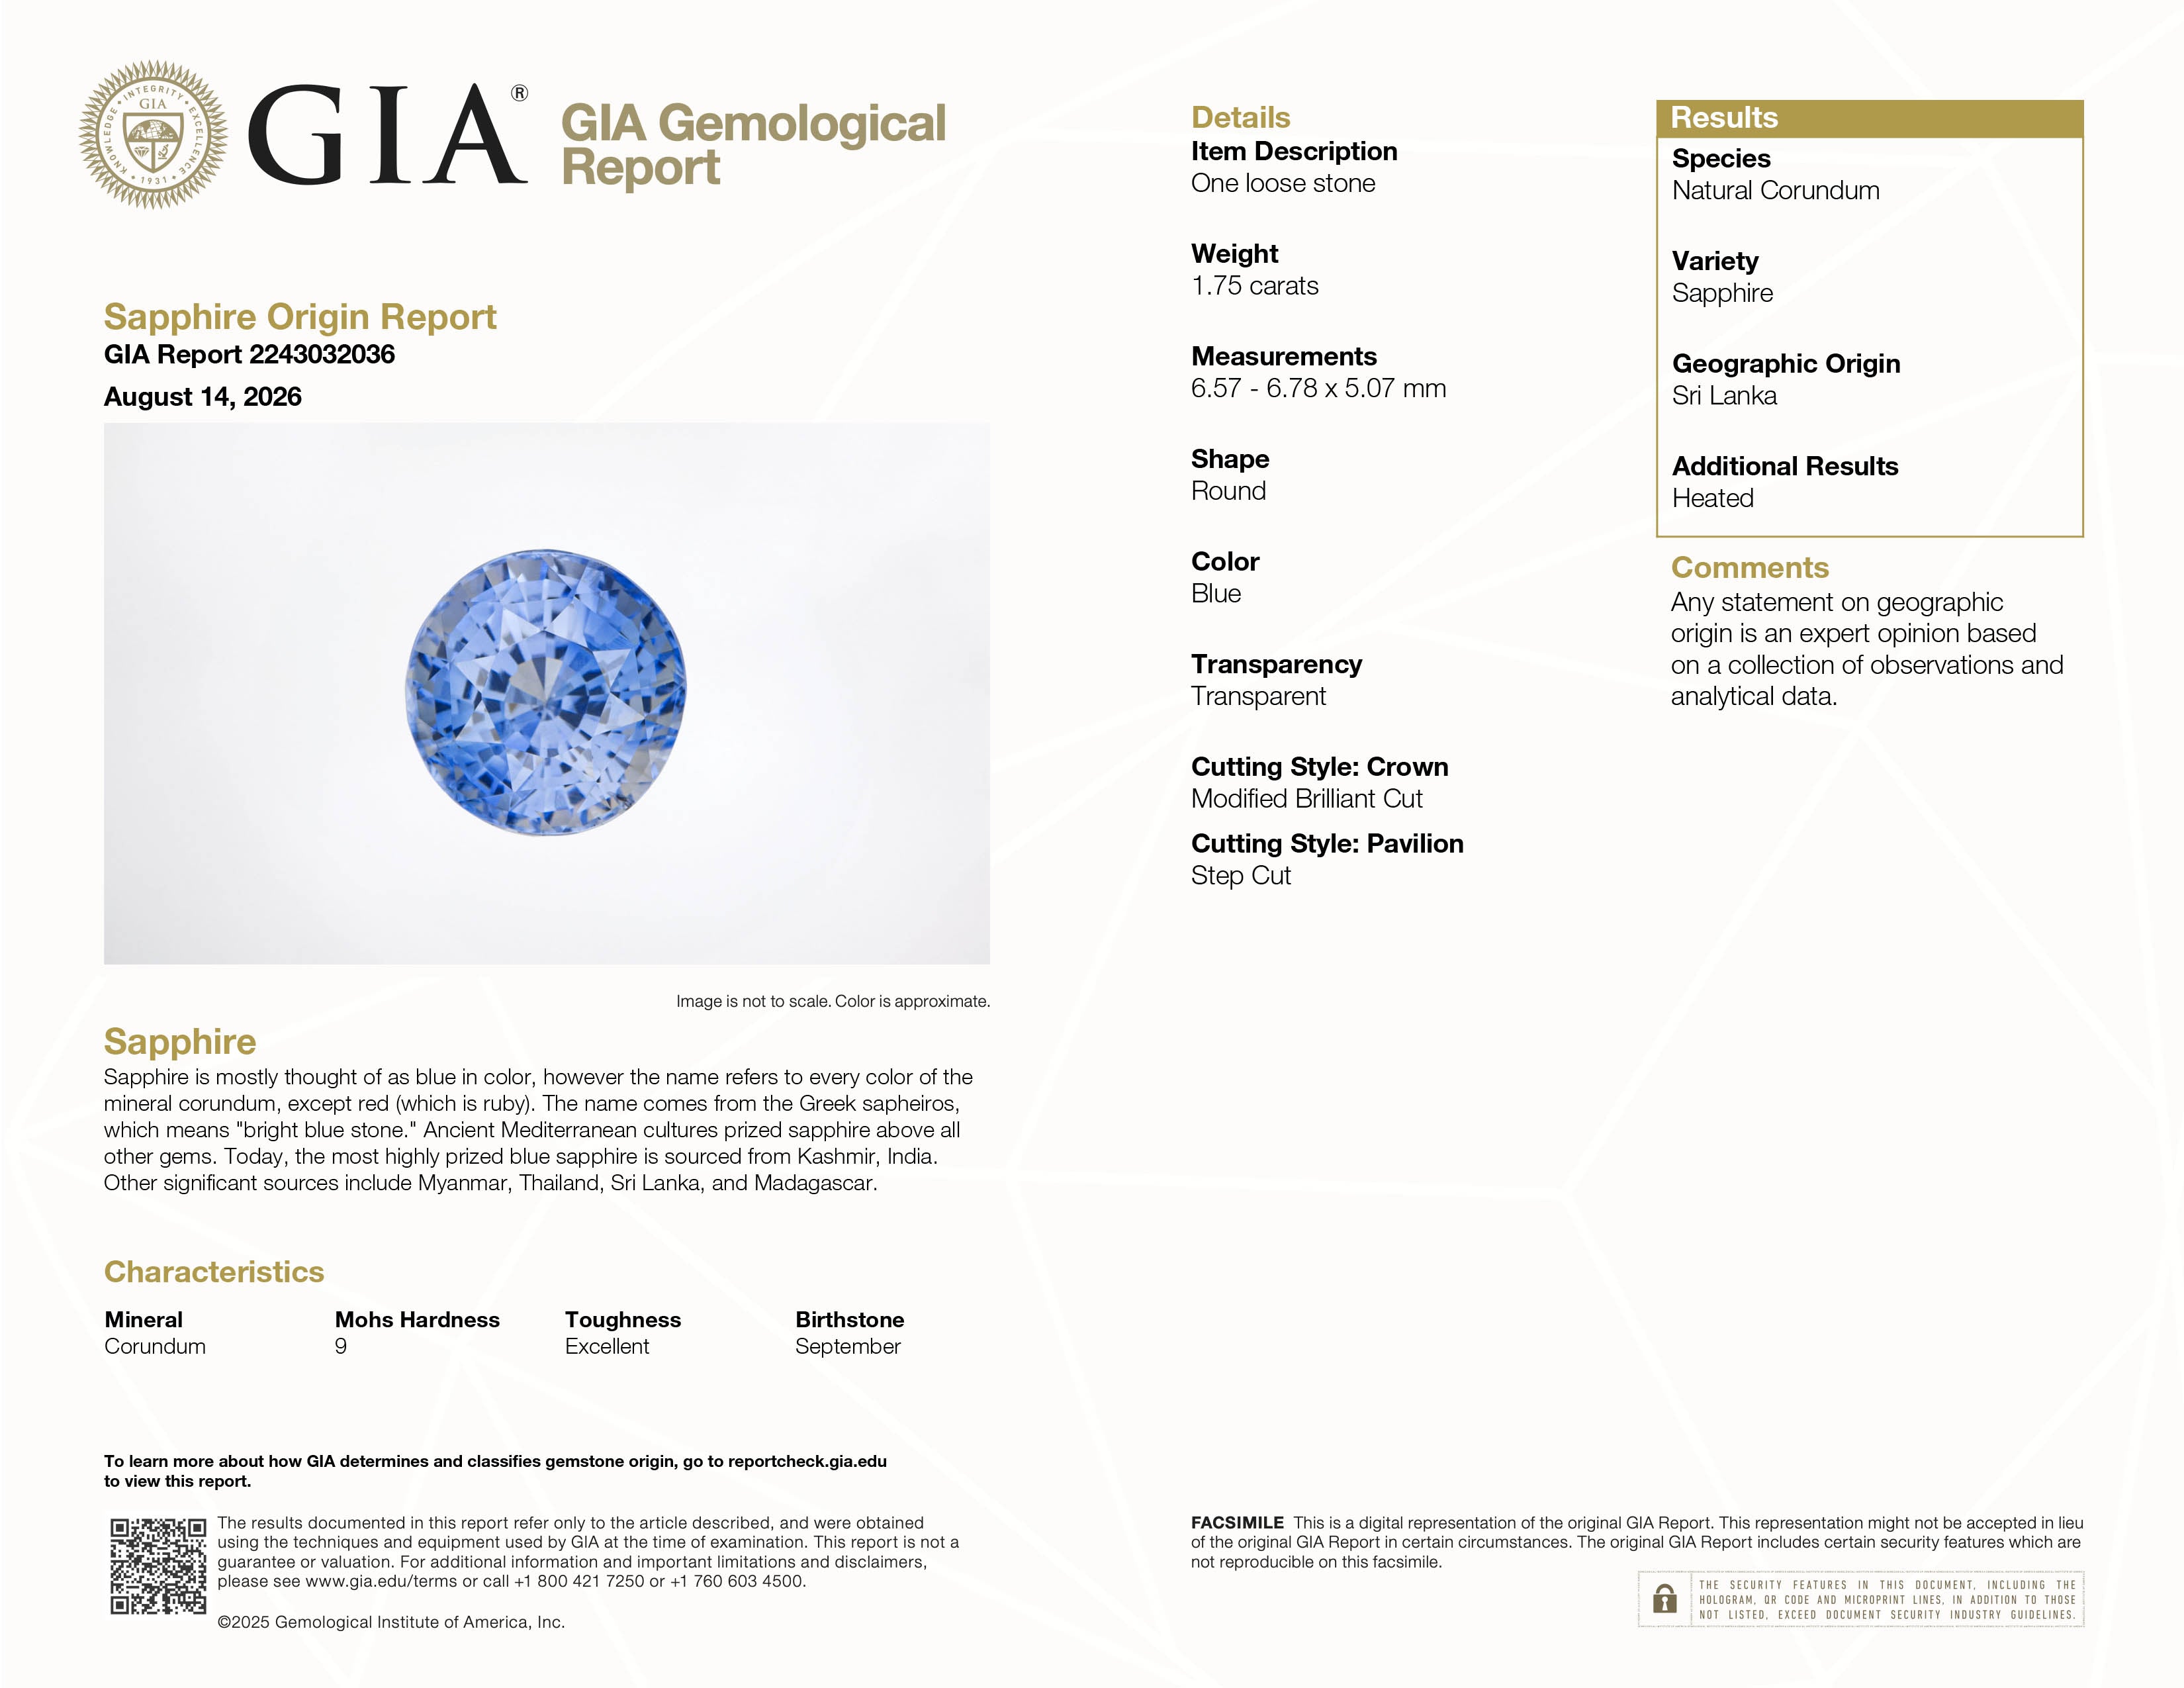
1.75ct スリランカ産ブルーサファイアのルース|加熱|GIA原産地レポート付き
CG8456
1.65ct 非加熱ルビーのルース|マダガスカル産ルビー・オーバル・GIA原産地レポート付き
CG8453
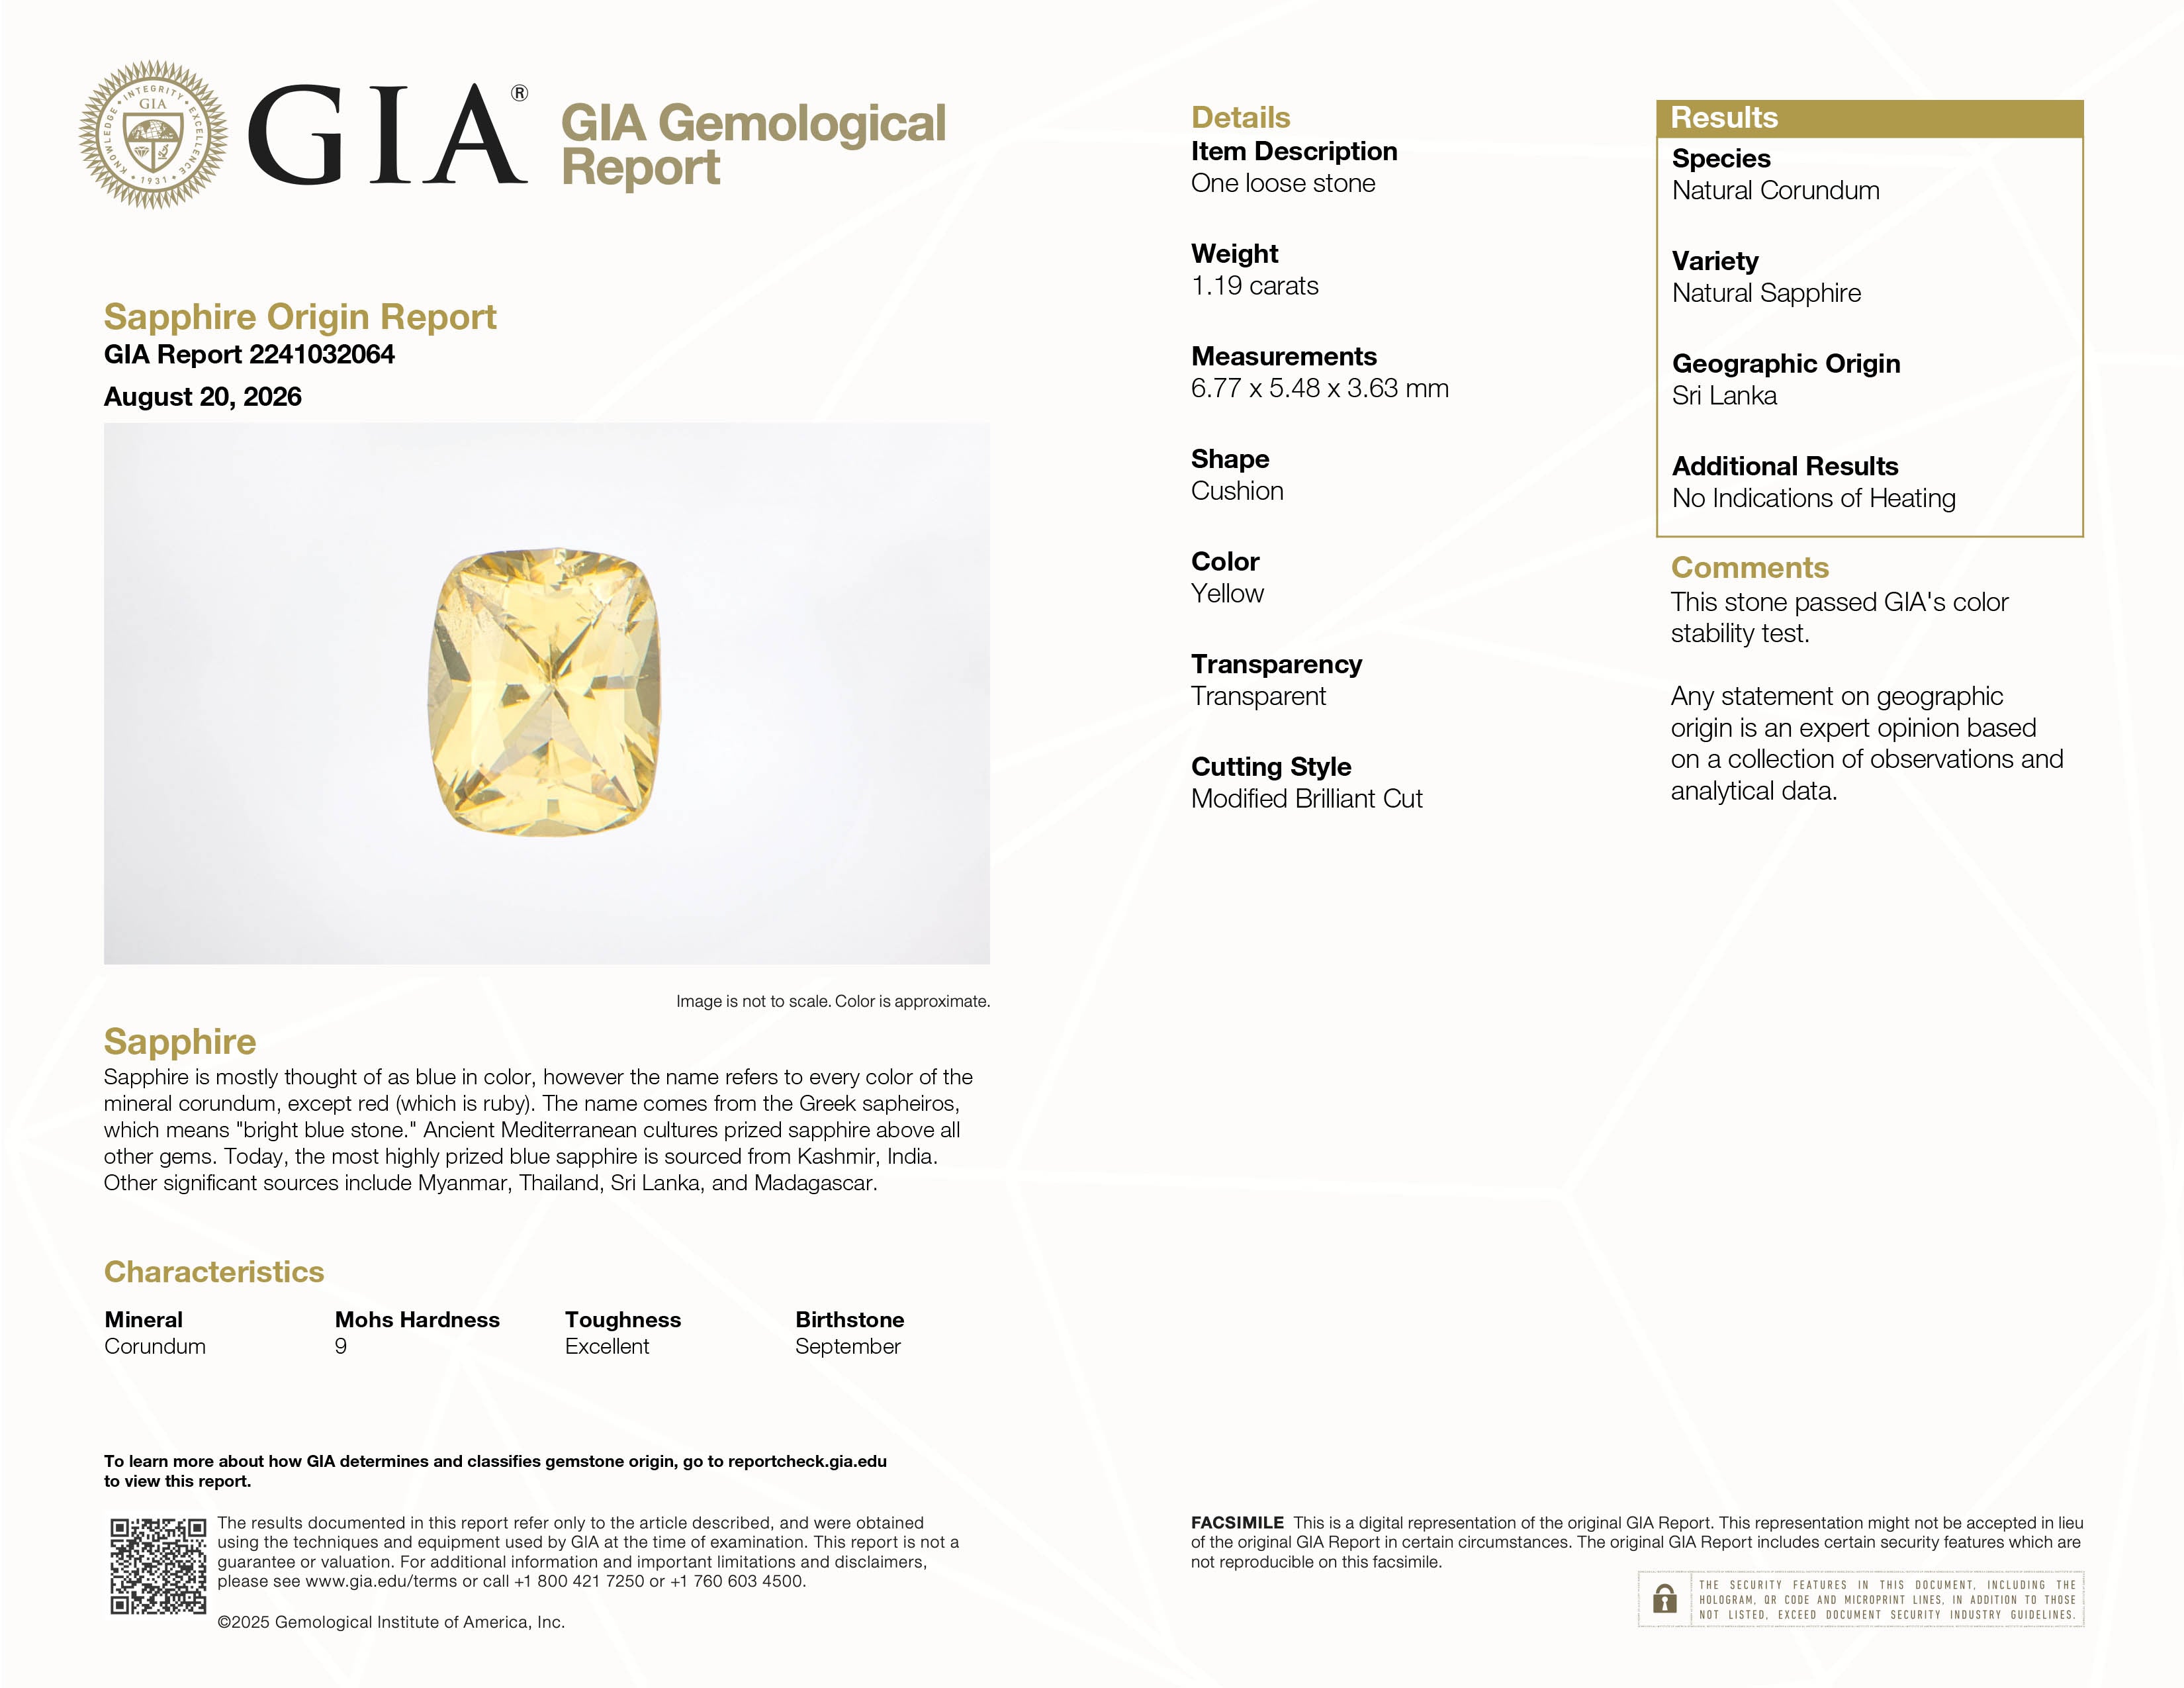
非加熱 イエローサファイア 1.19ct クッションカット|GIAレポート|スリランカ(セイロン)


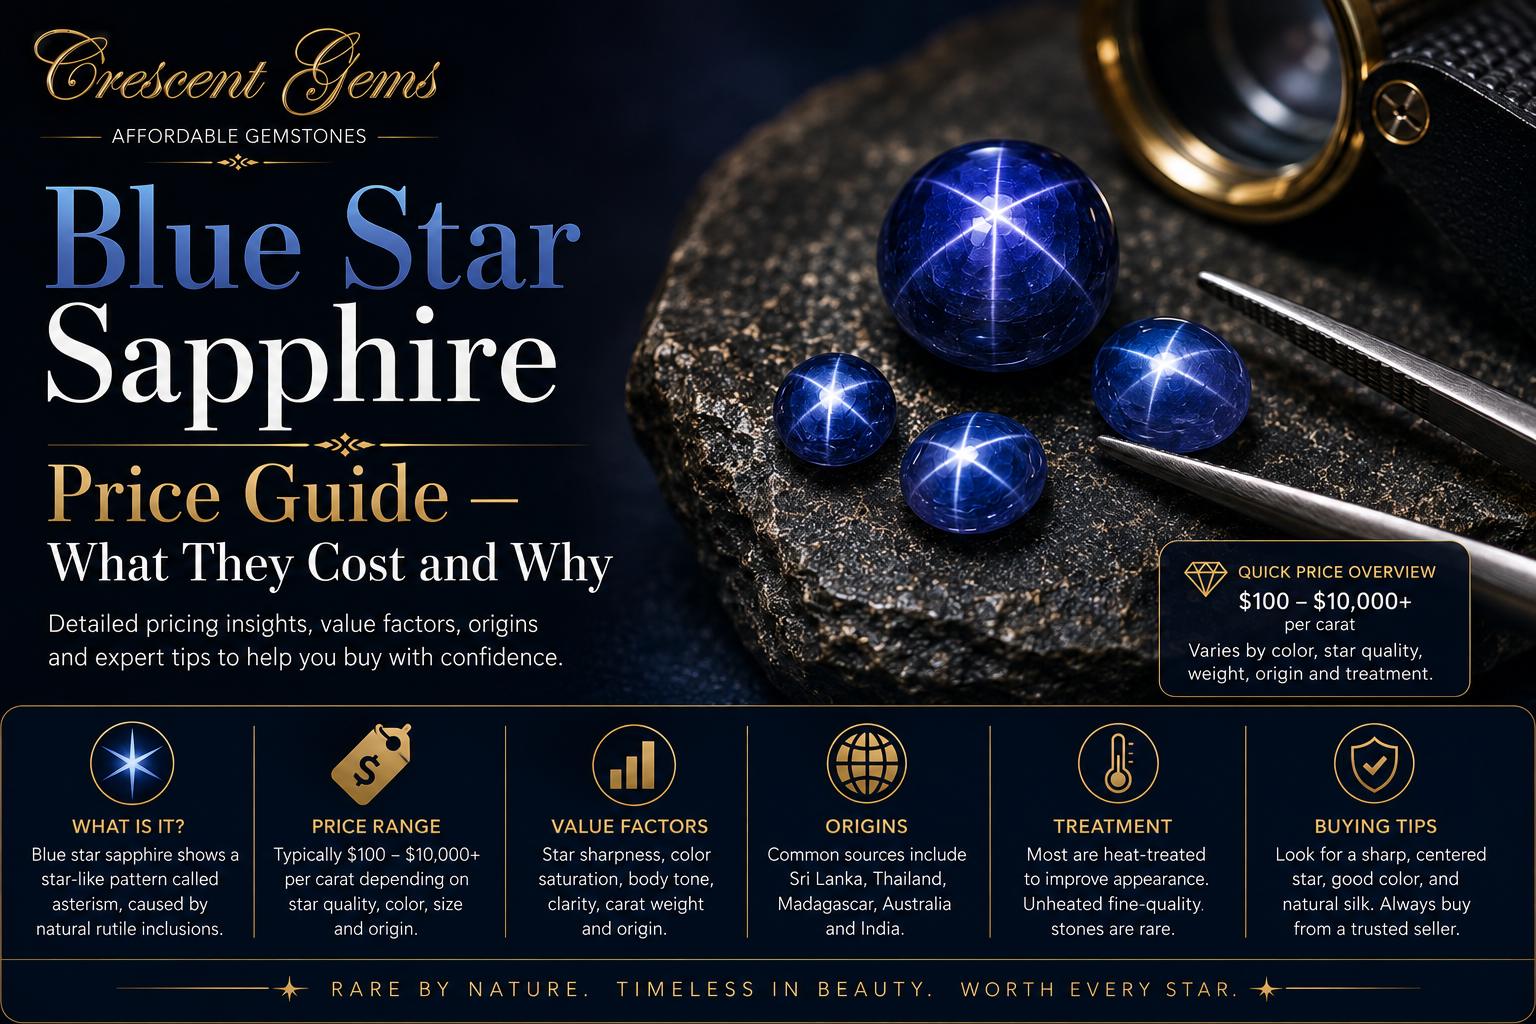
Blue Star Sapphire Price Guide — What They Cost and Why
もっと読むBlue Star Sapphire Price Guide — What They Cost and Whyについて
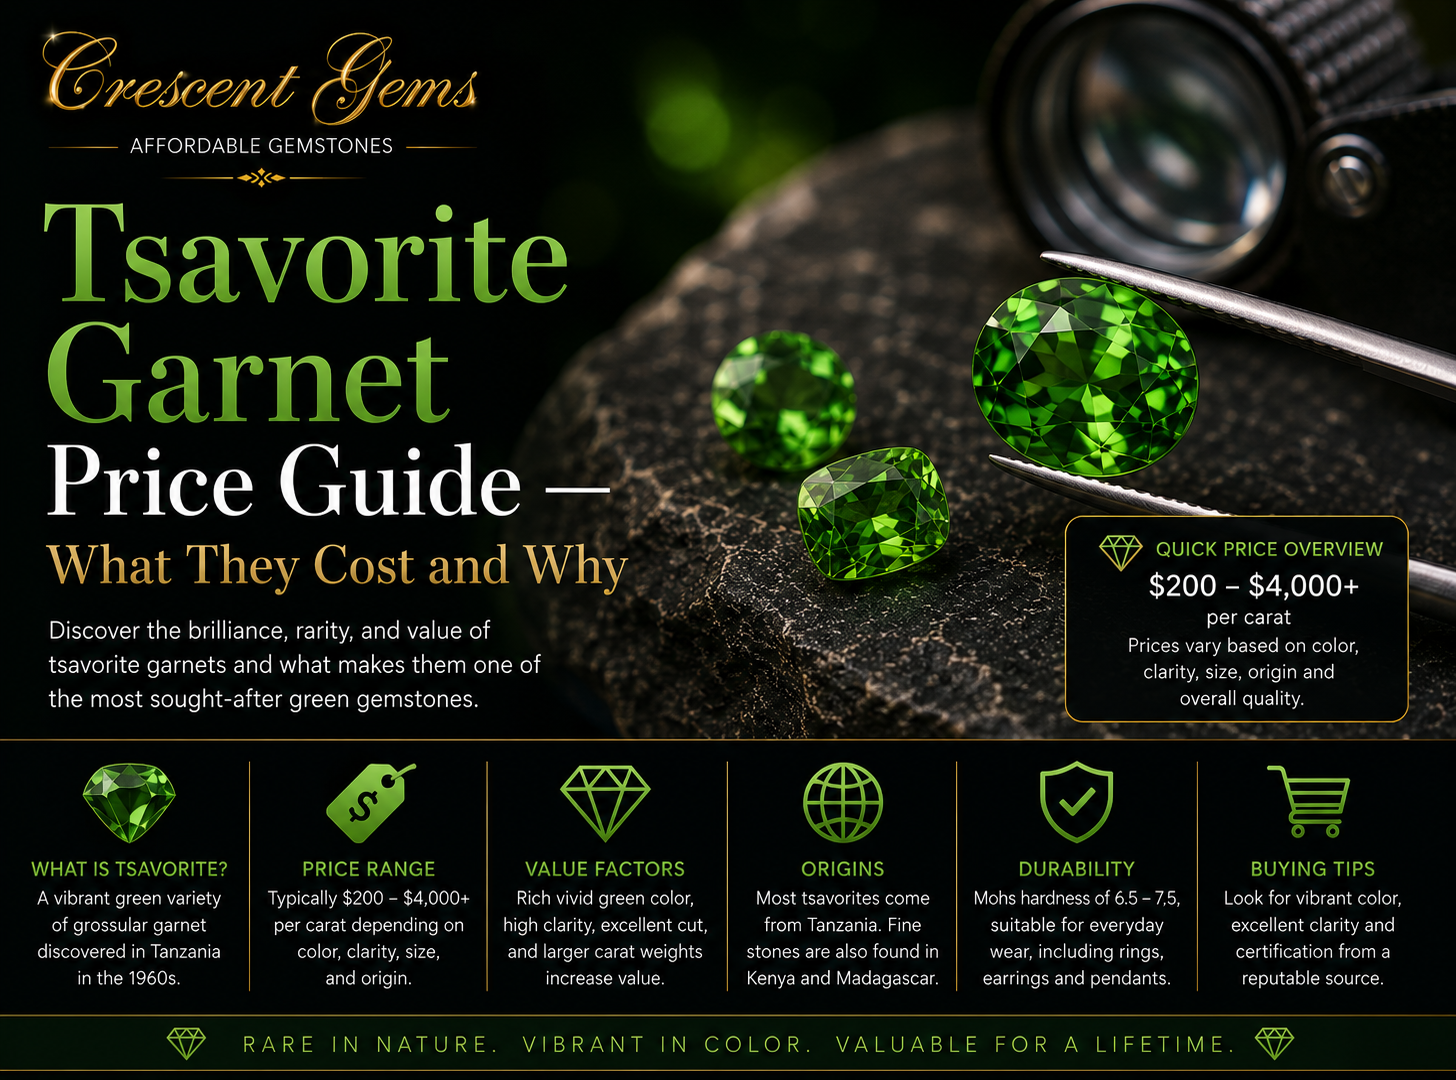
Tsavorite Garnet Price Guide — What They Cost and Why
もっと読むTsavorite Garnet Price Guide — What They Cost and Whyについて
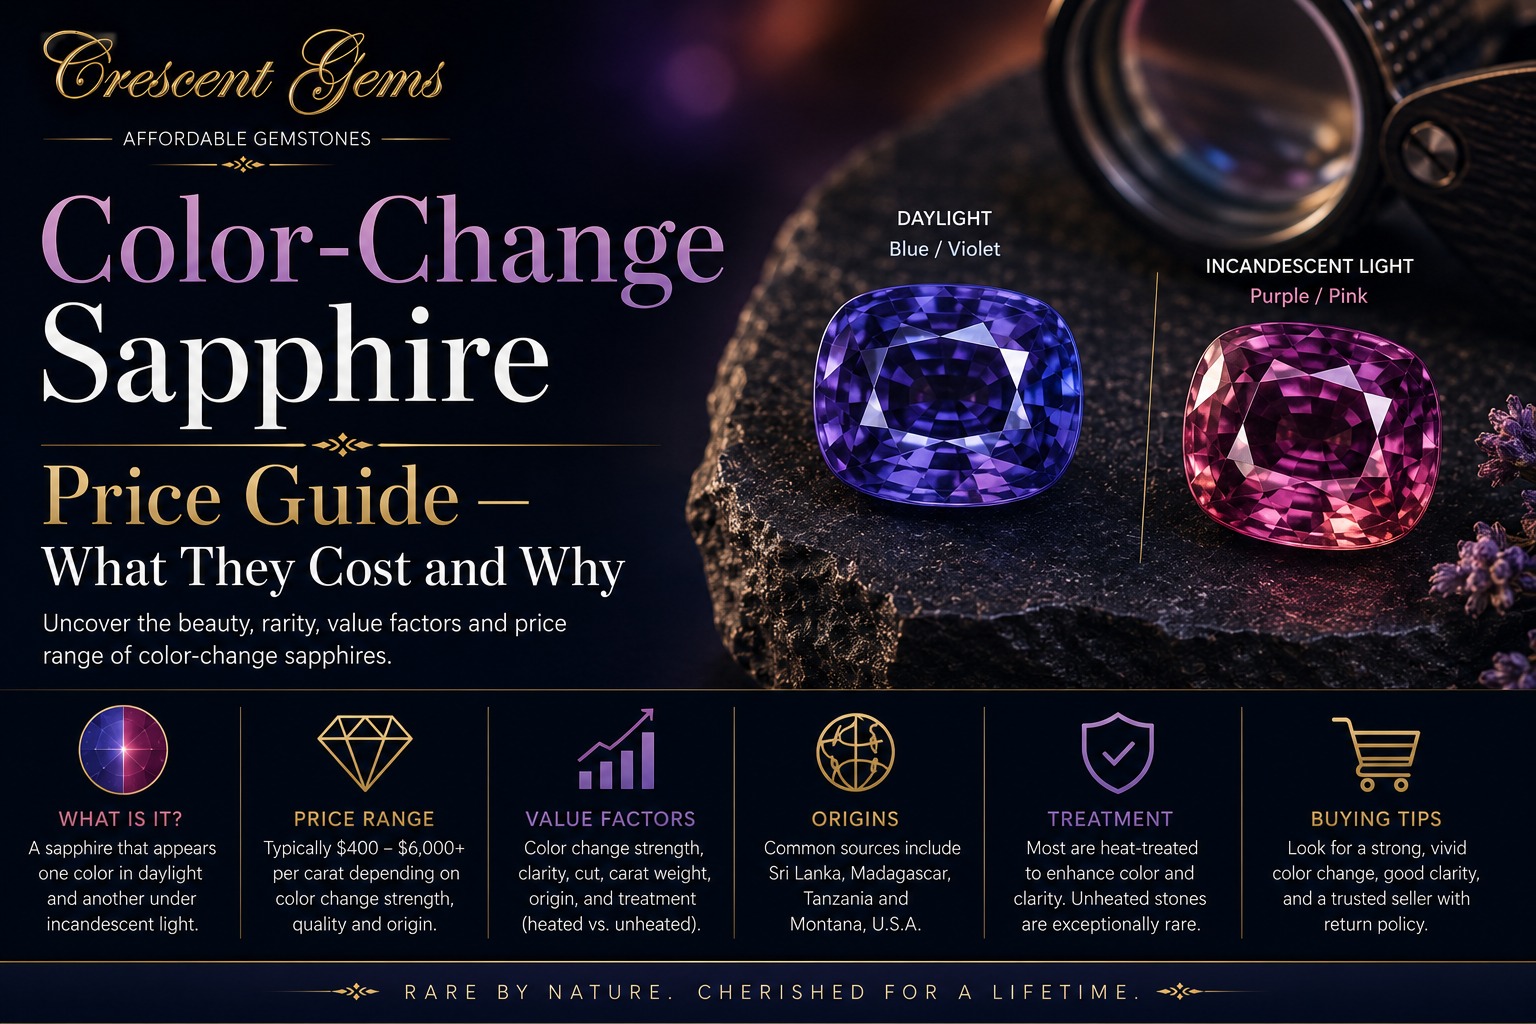
Color-Change Sapphire Price Guide — What They Cost and Why
もっと読むColor-Change Sapphire Price Guide — What They Cost and Whyについて
Is Cat's-Eye Chrysoberyl Good for an Engagement Ring?
もっと読むIs Cat's-Eye Chrysoberyl Good for an Engagement Ring?について
Cat's Eye Chrysoberyl Price Guide — What They Cost and Why
もっと読むCat's Eye Chrysoberyl Price Guide — What They Cost and Whyについて















Share: